The Crypto Top 10 Is a Graveyard. Bitcoin Isn’t.

People talk about “crypto” as if it were one asset class. It isn’t. I went back and looked at the ten largest coins by market cap at the end of 2016, then again at the end of 2021, and compared both lists with today’s market. The pattern is the same in both windows: the names churn, most of the leaders fade or disappear, and Bitcoin is still sitting at number one.

I believe Bitcoin is a store of value, though it is speculative too, for a different reason. The bet, in my view, is simply that it keeps succeeding and stays decentralized and secure. It is not trying to disrupt some other industry the way the other coins and projects are; those are bets on a business, and I see them as likely unregistered or unregulated securities that behave more like stocks. That is why I would only consider Bitcoin, and I regard every other coin as extremely speculative.

A note on the data before the tables. End-of-year ranks, prices, and market caps come from CoinMarketCap’s historical snapshots for December 31, 2016, and December 31, 2021. Today’s figures come from CoinGecko on November 14, 2026, at 1:52 p.m. CST for the 2021 comparison and today’s top 10, and at about 2:30 p.m. CST for the 2016 coins that aren’t in those tables. Every table is ranked by market cap, excluding stablecoins and tokenized real-world assets – Tether, USDC, and the like, and Figure Heloc, a tokenized home-equity product. Those are not coins meant to appreciate, so they were taken out, and the next-largest coins from the same snapshots were moved up. Size in this post always means market cap, not price. A coin can trade at half a dollar, or at a fraction of a cent, and still be worth more than a high-priced coin with a small supply. The gains and losses below are shown as both the change in price and the change in market cap, because those two numbers diverge when new coins are issued, burned, or unlocked. It was a down day – Bitcoin was off about 5% over 24 hours – so these are not flattering marks for anyone. Ethereum launched in July 2015, so the ten-year percentages catch its earliest, very young gains and flatter it; two other 2016 leaders, Ethereum Classic and Steem, were under a year old at that snapshot. The five-year comparison from the end of 2021 is the fairer test, because most of these coins were already established by then. And this is not investment advice.

The ten-year list

At the end of 2016, Bitcoin was already first by market cap, at $15.49 billion – $963.74 a coin. Ethereum was second, at $697 million, or $7.97 a coin. The rest of the top 10 was XRP, Litecoin, Monero, Ethereum Classic, Dash, MaidSafeCoin, Augur, and Steem. XRP is the clearest reminder that price is not size: it was third, with a market cap of $234 million, even though it traded at about six-tenths of a cent. No Tether. No BNB. No Solana. Several of those names barely come up anymore.

Top 10 at end of 2016 (by market cap) and how each has performed since, through Nov 14, 2026

#CoinLaunchedPrice
Dec 31, 2016
Price
Nov 14, 2026
Price change %
(Dec 31, 2016 →
Nov 14, 2026)
Market cap
Dec 31, 2016
Market cap
Nov 14, 2026
Market cap change %
(Dec 31, 2016 →
Nov 14, 2026)
Rank
Nov 14, 2026
1Bitcoin (BTC)Jan 3, 2009$963.74$65,580+6,704.7%$15.49B$1.319T+8,413.9%1
2Ethereum (ETH)Jul 30, 2015$7.9691$1,830.37+22,868.3%$697.0M$223.7B+31,995.9%2
3XRP (XRP)June 2012$0.006449$0.9512+14,649.6%$234.3M$60.4B+25,681.2%4
4Litecoin (LTC)Oct 7, 2011$4.3253$45.21+945.2%$212.5M$3.52B+1,555.1%18
5Monero (XMR)Apr 18, 2014$13.78$496.72+3,504.6%$188.3M$9.36B+4,869.5%9
6Ethereum Classic (ETC)Jul 20, 2016$1.4131$5.96+321.8%$123.5M$947.1M+666.8%51
7Dash (DASH)Jan 18, 2014$11.21$36.21+223.0%$78.3M$466.9M+495.9%81
8MaidSafeCoin (MAID)Apr 22, 2014$0.09933——$45.0M——Delisted
9Augur (REP)2015 (token)$3.7748——$41.5M——Unranked
10Steem (STEEM)Mar 24, 2016$0.1695$0.04205−75.2%$38.9M$23.7M−39.2%690*

Ranked by market cap, excluding stablecoins and tokenized real-world assets.

The price change is what a holder of one coin gained or lost over that period.

Combined market cap of this top 10 at the end of 2016: $17.15 billion. MaidSafeCoin is no longer listed on CoinGecko, and CoinMarketCap no longer shows a live market price. Augur’s original token is unranked on CoinGecko (market cap reported as $0, almost no volume); the project has since moved through later token migrations. Those two are not given a clean buy-and-hold return. “Rank now” is today’s rank by market cap on the same excluded-stable, excluded-RWA basis. Steem’s 690* is CoinGecko’s overall rank, which still includes stables.

Only four of those ten are still in today’s top 10: Bitcoin, Ethereum, XRP, and Monero. That’s it.

Bitcoin is up 6,705% in price over those ten years, from $964 to $65,580 – about 68 times your money if you simply held it – and its market cap went from $15.49 billion to $1.319 trillion, up 8,414%. Ethereum’s percentage gain is even larger, because it started at $8, though it has given back half its value since the end of 2021. That ten-year Ethereum figure is real, but it is also flattering: Ethereum launched in July 2015, so the comparison captures its earliest, very young gains. It was only 17 months old at the end of 2016. Two other 2016 leaders were even younger. Ethereum Classic had only existed as a separate coin since the July 2016 fork, about five and a half months. Steem had launched in March 2016, about nine months earlier. XRP is up about 147 times in price, and much more than that in market cap, because a lot more XRP is in circulation now. Litecoin, Monero, Ethereum Classic, and Dash are also up over the full decade, in both price and market cap, and Monero has climbed back into the top 10, in 9th, just ahead of Dogecoin. That is the honest 10-year picture: several of those early coins made people money if they bought in 2016 and never sold. The fairer test of a “large coin” as an established asset is the five-year window that starts at the end of 2021.

But “up” and “still a leader” are different things. Litecoin has fallen from 4th to 18th. Ethereum Classic is 51st. Dash is 81st. Steem is down 75% in price, 39% in market cap, and ranks far down the list. MaidSafeCoin is gone from the major listings. Augur’s original token is unranked. Six of the 2016 top 10 are no longer top-10 assets, and two of those are effectively gone from the market that used to treat them as blue chips.

If you had assumed the top 10 was a durable club, you would have been wrong. Over a few years, that list is a graveyard. Bitcoin is the name that stayed at the top, by market cap, the whole way through.

Then came 2021

The more painful test is what happened after the last mania. By December 31, 2021, Bitcoin was $46,306, with a market cap of $875.9 billion. Ethereum was $3,683, at $438.1 billion. Solana, Cardano, Terra, Avalanche, Polkadot, and Dogecoin had muscled into the top 10. If you bought that list and held it, you were not buying one thing called “crypto.” You were buying a mixed bag, and most of the bag got cheaper.

Top 10 at end of 2021 (by market cap) and how each has performed since, through Nov 14, 2026

#CoinLaunchedPrice
Dec 31, 2021
Price
Nov 14, 2026
Price change %
(Dec 31, 2021 →
Nov 14, 2026)
Market cap
Dec 31, 2021
Market cap
Nov 14, 2026
Market cap change %
(Dec 31, 2021 →
Nov 14, 2026)
Rank
Nov 14, 2026
1Bitcoin (BTC)Jan 3, 2009$46,306$65,580+41.6%$875.9B$1.319T+50.6%1
2Ethereum (ETH)Jul 30, 2015$3,683$1,830−50.3%$438.1B$223.7B−48.9%2
3BNB (BNB)Jun 26, 2017$512$589.15+15.1%$85.4B$77.5B−9.2%3
4Solana (SOL)Mar 16, 2020$170$72.07−57.7%$52.7B$42.6B−19.1%5
5Cardano (ADA)Sep 29, 2017$1.31$0.1541−88.2%$43.9B$5.79B−86.8%14
6XRP (XRP)June 2012$0.83$0.9512+14.4%$39.5B$60.4B+52.9%4
7Terra (LUNA)*Apr 23, 2019$85.47~$0−99.99996%$30.9B$192.3M−99.4%124
8Avalanche (AVAX)Sep 22, 2020$109$7.41−93.2%$26.6B$3.31B−87.6%19
9Polkadot (DOT)May 26, 2020$26.72$0.7459−97.2%$26.4B$1.28B−95.2%44
10Dogecoin (DOGE)Dec 6, 2013$0.1705$0.05965−65.0%$22.6B$9.35B−58.7%10

Ranked by market cap, excluding stablecoins and tokenized real-world assets.

The price change is what a holder of one coin gained or lost over that period.

Combined market cap of this top 10 at the end of 2021: $1.642 trillion. *Terra collapsed in May 2022. The original coin now trades as Terra Classic (LUNC) at $0.00003483, with a market cap of $192.3 million.

Bitcoin is up 41.6% in price since the end of 2021, and 50.6% in market cap, and it still ranks first. It is not the only 2021 leader with a gain, and market cap and price do not always tell the same story. XRP is up 14.4% in price and 52.9% in market cap – a slightly larger cap gain than Bitcoin’s – but more XRP came into circulation, which lifts market cap even when the price move is smaller. BNB’s price is up 15.1%, yet its market cap is down 9.2%, because the circulating supply shrank as tokens were burned. Ethereum is down 50% in price and 49% in market cap. Solana is down 58% in price but only 19% in market cap, because a lot more SOL was issued. Cardano has lost 88% of its price and fallen to 14th. Polkadot, 9th at the end of 2021, has lost 95% of its market cap and fallen to 44th. Avalanche has lost 93% of its price and 88% of its market cap. Dogecoin is still in today’s top 10, but it is down 65% in price and 59% in market cap. Terra collapsed in May 2022. The original coin now trades as Terra Classic (LUNC) at a fraction of a cent, with a sliver of its old market cap.

That is the buy-and-hold lesson people skip when they treat every large coin as if it were Bitcoin. A coin can be huge by market cap at the top of a cycle and still be a bad five-year hold. The 2021 top 10 was a poster of that.

Today’s top 10

Top 10 on Nov 14, 2026 (by market cap) and how each has performed since Dec 31, 2021

#CoinLaunchedPrice
Dec 31, 2021
Price
Nov 14, 2026
Price change %
(Dec 31, 2021 →
Nov 14, 2026)
Market cap
Dec 31, 2021
Market cap
Nov 14, 2026
Market cap change %
(Dec 31, 2021 →
Nov 14, 2026)
1Bitcoin (BTC)Jan 3, 2009$46,306$65,580+41.6%$875.9B$1.319T+50.6%
2Ethereum (ETH)Jul 30, 2015$3,683$1,830−50.3%$438.1B$223.7B−48.9%
3BNB (BNB)Jun 26, 2017$512$589.15+15.1%$85.4B$77.5B−9.2%
4XRP (XRP)June 2012$0.83$0.9512+14.4%$39.5B$60.4B+52.9%
5Solana (SOL)Mar 16, 2020$170$72−57.7%$52.7B$42.6B−19.1%
6TRON (TRX)Jun 25, 2018$0.07540$0.31+308.7%$7.68B$29.3B+281.4%
7Hyperliquid (HYPE)Nov 29, 2024n/a$65.15Newn/a$15.5BNew
8Zcash (ZEC)Oct 28, 2016$147$850.18+480.1%$1.97B$14.49B+636.7%
9Monero (XMR)Apr 18, 2014$229$496.72+117.1%$4.13B$9.36B+126.5%
10Dogecoin (DOGE)Dec 6, 2013$0.1705$0.05965−65.0%$22.6B$9.35B−58.7%

Ranked by market cap, excluding stablecoins and tokenized real-world assets.

The price change is what a holder of one coin gained or lost over that period.

Combined market cap of this top 10: $1.801 trillion. TRON was 26th at the end of 2021. Hyperliquid launched in November 2024. Zcash was 68th at the end of 2021; Monero was 42nd. Prices and market caps are from 1:52 p.m. CST on a down day.

Six of the 2021 names are still in the top 10: Bitcoin, Ethereum, BNB, XRP, Solana, and Dogecoin. Four coins from that 2021 list dropped out: Cardano, Terra, Avalanche, and Polkadot. The four that replaced them are TRON, which has climbed from 26th at the end of 2021 on a 309% price gain; Hyperliquid, which launched in 2024; Zcash, which was 68th at the end of 2021; and Monero, a 2016 leader that has returned to the top 10.

From the 2016 list, four names are still there: Bitcoin, Ethereum, XRP, and Monero. Six of the ten largest coins of 2016 did not survive as top-10 assets.

I don’t say “Bitcoin only goes up.” I have never said that. Bitcoin can drop 50%, and it was down hard again today. The point is narrower, and the tables make it: “crypto” is not one bet. The top 10, ranked by market cap, churns. Most of the names that look permanent at the peak are not. Bitcoin has kept the number one slot, by market cap, through both of these windows, and it is the 2021 leader that delivered a real price gain without depending on a shrinking or expanding supply to tell the story.

If you are going to buy and hold, know which asset you are actually holding. A ticker that was seventh in 2016 or ninth in 2021 is not a substitute for Bitcoin just because it showed up on the same list.

Sources

CoinMarketCap historical snapshot, December 31, 2016

CoinMarketCap historical snapshot, December 31, 2021

Today’s prices, market caps, and ranks: CoinGecko, November 14, 2026 (1:52 p.m. CST for the 2021 and current top-10 tables; about 2:30 p.m. CST for the other 2016 coins).

Launch dates are the genesis block or mainnet launch for layer-1 coins, and the token or ICO launch for tokens (for example BNB’s June 2017 ICO, and Hyperliquid’s November 2024 token launch). Ethereum Classic is dated to the July 2016 fork, when it became a distinct asset. Sources include official project posts and CoinGecko genesis dates; the companion fact document lists each source in full.

This is not investment advice. It is a historical comparison of market prices and market caps. Do your own research, and don’t invest money you can’t afford to lose.
11 Empty Seats: Who Really Saved Pete Hegseth?

On Tuesday afternoon, the House voted 211-204 to send Rep. Thomas Massie’s articles of impeachment against Defense Secretary Pete Hegseth to the Judiciary Committee. In plain English, that vote buried the impeachment for the rest of this Congress.

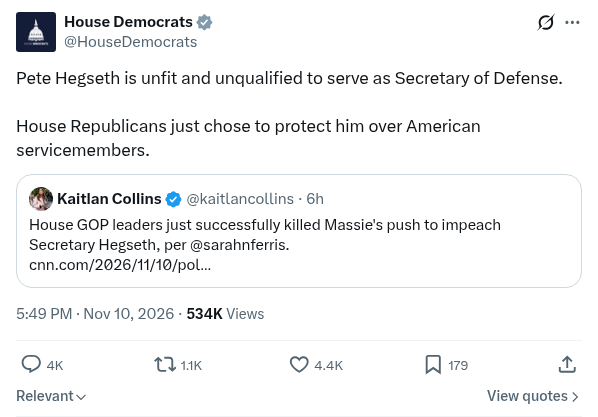
Within minutes, House Democrats posted their talking point: “Pete Hegseth is unfit and unqualified to serve as Secretary of Defense. House Republicans just chose to protect him over American servicemembers.”

House Democrats X post from November 10, 2026, saying Republicans chose to protect Pete Hegseth over American servicemembers.
House Democrats post, 5:49 p.m. ET, Nov. 10, 2026.

Read that again. The party that posted this lost the vote by seven, and eleven of its own members weren’t in the room. If those eleven had shown up and voted no, the motion fails 215-211. You don’t get to call a vote a test of whether Congress protects servicemembers and then not show up for it. That isn’t a stand. It’s a press release.

Before you take any of it at face value, look at the roll call.

The numbers (House Clerk, Roll Call 317, H. Res. 1655). A “yes” vote sent the impeachment to committee to die. A “no” vote kept it alive:

  • Republicans: 210 yes, 1 no (Massie), 7 not voting.
  • Democrats: 0 yes, 203 no, 11 not voting.
  • The one independent voted yes.

The eleven Democrats who weren’t there: Julia Brownley (CA), Lou Correa (CA), Laura Gillen (NY), Steven Horsford (NV), Jonathan Jackson (IL), Nancy Pelosi (CA), Brittany Pettersen (CO), Melanie Stansbury (NM), Haley Stevens (MI), Marilyn Strickland (WA), and Frederica Wilson (FL).

The excuses started falling apart the next day.

Correa had a medical procedure and wasn’t in Washington. That’s a real explanation.

Pelosi does not get the same pass. Her office said she returned to San Francisco the day of the vote for a Veterans Day event, her last as a member of Congress, and that she would have voted no. She was still a sitting member. The vote was on the calendar. A farewell event in the district is not more important than showing up for a vote her own party called a test of whether Congress protects servicemembers.

Jackson is a different story. On Tuesday night he said a traffic incident and a police-escorted bus kept him from reaching the chamber. A TMZ reporter, Charlie Cotton, says he saw Jackson on the Capitol steps around 5:57 or 5:58 p.m., filming a video that never went up, with the vote closing at 6:02. I haven’t independently verified that clip. But when Cotton confronted him the next day, Jackson didn’t deny being there. He called missing the vote “inexcusable,” still mentioned a traffic jam, and then said, “I wish I could answer you in any more detail.” He later told ABC7 Chicago he was already on the Hill and got delayed answering questions from reporters. That’s not stuck in traffic on the way in. That’s being there and not walking into the chamber.

Stansbury and Gillen still blame the same police escort. Strickland’s chief of staff told ABC News they missed it by one minute waiting for a motorcade. Pettersen said she was “denied the ability to vote” and didn’t explain. Members had known for at least 18 hours that a 5:30 p.m. vote series was on the calendar, and the vote itself, scheduled for 15 minutes, was held open for 29.

After the referral vote closed, six of the eleven made the very next vote: Brownley, Gillen, Jackson, Pettersen, Stansbury, and Strickland. Even if those six had been there, the motion still passes 211-210. Horsford made the vote after that. Stevens and Wilson still didn’t show. Stevens, a lame duck who lost her Senate primary and then endorsed the Republican in that race, skipped every Tuesday vote. Wilson missed Monday and Tuesday over health issues and was there Wednesday.

Seven Republicans skipped too: Monica De La Cruz (TX), Neal Dunn (FL), Russell Fry (SC), Julia Letlow (LA), Tom Tiffany (WI), Derrick Van Orden (WI), and Rudy Yakym (IN). If all eighteen absent members had voted with their parties, the motion still passes 218-215. And even if it had failed, impeachment would have needed its own separate vote.

And give credit where it’s due. The only Republican willing to break ranks was Thomas Massie, the guy who wrote the resolution. He did his job. He voted his conscience against his own party, and he did it on the record.

This is the part of politics I can’t stand. One side blames the other for an outcome its own absences helped produce. The other side closes ranks to avoid an uncomfortable vote. And the voter is left with a press release instead of the truth.

Here’s my ask. Don’t outsource your judgment to a party account on X, whether it’s red or blue. The roll call is public. Look up how your representative voted, or whether they bothered to vote at all. Accountability starts with showing up.

Sources:

Young People Aren’t Rejecting Free Markets. They’ve Never Seen One.

Bloomberg recently ran a segment asking “Why Capitalism Is Losing Young Americans,” with David Westin, Paul Ryan and Steven Rattner. You can watch it here: https://youtu.be/7Kfe-dEEPO4

The question itself is the problem. Asking why people are moving away from free-market capitalism assumes we have free-market capitalism. We don’t. We have crony capitalism.

To be fair, the panel gets close. They admit affordability is a real problem. They list the price shocks: COVID spending, overspending in Washington, tariffs, and the oil spike from the Iran war. They even concede that neither party is selling free markets anymore, and that Trump governs as a protectionist, not a free-marketer.

But they never take the next step. Not once do they say “crony capitalism,” “corporate welfare,” “bailouts,” or “regulatory capture.” Their fix is better PR for capitalism and more pro-growth policy. That misses the point.

Here is what a young person actually sees:

  1. Bailouts for big banks and corporations when they fail, while regular people and small businesses go bankrupt when they do.
  2. Tariffs that raise their prices to protect favored industries.
  3. Regulations written by and for the incumbents they are supposed to police.
  4. Money printed to keep asset prices up, while they can’t afford a house.
  5. Campaign cash from big donors and lobbies buying outcomes in both parties.

That isn’t a free market. It’s a rigged one. When young people say capitalism isn’t working for them, they’re describing that system accurately. The mistake is reaching for socialism, which hands even more power to the same insiders.

The answer isn’t to defend the current system harder. It’s to actually try free markets: end the bailouts, end the tariffs, stop the money printing, and get the lobbyists out of writing the rules. Sound money and real competition would do more for affordability than any slogan from either party.

Don’t let anyone tell you you’re rejecting free enterprise. You’re rejecting cronyism. So am I.

Democrats: Three Clean Bills. Make Trump Choose.

Democrats: focus on these three issues. Give each its own clean, single-topic bill.

1. End the Iran war.

Congress needs to exercise its authority and bring American involvement to an end. Stop arguing over what to call the conflict and work on ending it.

2. End the tariffs.

Stop making American consumers and businesses pay these taxes on imports. Put ending the tariffs in a standalone bill.

3. Ban individual stock trading by presidents and members of Congress.

Write a real ban with clear enforcement and no loopholes. Public officials should serve the country, not trade individual stocks while making decisions that affect their value.

No pork-barrel spending.
No unrelated riders.
No poison pills.

These issues aren’t unanimous, but each deserves a clear vote without unrelated baggage.

Build the votes in both chambers. Get the bills to Trump’s desk. Make him sign them, let them become law without his signature, or veto them and explain why.

If Congress blocks them, let the public see who stood where.

Less political theater. More results for everyday people.

A Letter to Iowa’s New Democrats, and Every Democrat: What to Work On and What to Leave Alone

Amazing clarity the VP has gained overnight! Here is his post on X.

But everyone knows why we lost. And any honest conversation about where we go from here must start there.

  1. End the war
  2. Focus on cost of living/inflation
  3. Put America First
  4. Change our relationship to Israel

Show us over the next 2 years! Here is my letter to the Democrats:

Dear Senator-elect Turek, Congresswoman-elect James, and Democrats across the country,

Congratulations on winning in Iowa. I’m a 37-year-old moderate voter in Cedar Falls who doesn’t feel claimed by either party. I’m writing to say what I and many voters like me want from you, and what we don’t.

The exit polls say the same thing. Voters ranked the economy first, and about 75 percent called it poor. Sixty-three percent said the Iran war was the wrong decision. Voters of both parties want Congress to focus on lowering costs and ending the war, not on investigating or backing Trump.

What To Work On

1. End the Iran war. Both of you said it has raised gas and diesel prices. Congress should vote to end it and get back to diplomacy.

2. Release the Epstein files. Release them in full, and let the public see who was involved. Josh, you’ve already said this. Lindsay, I’d like to hear where you stand. Every Democrat should make this a clear, public commitment.

3. Keep the border secure. Secure borders, more immigration judges, and deporting violent criminals aren’t extreme. They’re what a country expects of its government. Both of you have said it, and your party should say it too.

4. Lower everyday costs. Gas, groceries, health care and housing are what decided this election. Cost-worried voters broke heavily your way, and Democrats are now trusted more on the economy. Keep that trust.

5. Clean up Congress. Ban members from trading individual stocks, ban them from becoming lobbyists, and keep corporate PAC money out. Lindsay, you promised the stock ban on day one, so please do it. Term limits belong on the table too.

6. Take the deficit seriously. Fixing health care and costs only lasts if the money behind it is sound.

What To Leave Alone

1. Transgender issues. Most voters don’t care about this, and it’s not what they sent you to Washington to do.

2. Culture-war fights in general. Spending your time on them hands the other side a gift. Govern for a pluralistic country and don’t enforce ideological conformity.

3. Constant attacks on Trump as your main message. Voters didn’t pick you for being against someone. They picked you for what you’d fix.

You won because you talked about costs, corruption and the war. Keep doing that, and keep your promises.

Respectfully,
Axel Hoogland
Cedar Falls, Iowa

Chapter 5 — A Shareholder Society – The Commonwealth

Listen Here on Spotify

The people who can’t wait

Everything so far has a quiet assumption buried in it: time. The seed works because a newborn has sixty years for eighteen thousand dollars to become a million. The scale-threshold rule works because it catches the giant companies of the future as they cross the line. Both are patient mechanisms, and patience is a luxury of the young and the not-yet-born.

But most of the country is neither. The person reading this is probably somewhere between twenty and sixty, with a job, a mortgage, some retirement savings that won’t be enough, and nowhere near sixty years left for compounding to do its work. The seed can’t help them; they’re already born. The scale-threshold can’t help them; it fills accounts that don’t yet have their name on them. If the shareholder society only ever reaches the newborns, then everyone alive today spends the rest of their life watching a good idea arrive one generation too late.

So this is the chapter about the people who can’t wait — the hardest problem in the book, and the one I’ve been promising to face instead of dodge. How does someone who’s already forty get a real stake in the productive economy, starting now?

There’s only one honest answer, and it’s the word I’ve been circling the whole way: redistribution.

Redistribute the growth

Right now the bottom half of Americans own about one percent of the stock market — one percent total, split among a hundred and sixty million people. Effectively nothing. The goal of this whole project, put plainly, is to change that: every adult owning a real, meaningful piece of the productive economy — a stake worth tens of thousands of dollars at least, enough that ownership is a fact of their life rather than something only other people have. Keep your eye on that floor, not on the gap between top and bottom. This was never about making the rich less rich. It’s about giving the people at the bottom something real to own.

We do take some of the existing pile: a small slice each year, a larger one at death. But we take it slowly, and the economy grows faster than we take it, so the people at the top keep getting richer in dollars even as their share of it shrinks. We aren’t clawing back the fortunes that exist. We’re redistributing the growth on top of them — bending who gets the next trillion, not seizing the last one.

The economy will be far larger in sixty years than it is today — the one safe bet in the whole book. Money left in the market and reinvested has historically doubled in real terms about every decade, so over sixty years the pie doesn’t just grow, it grows many times over. Everyone who owns a piece rides that same curve. The top ten percent, who hold about 87 percent of the market, end up many times richer in real dollars than they are now — and, I won’t pretend otherwise, they stay right around 87 percent, because they compound alongside everyone else. This does not shrink their slice. What it does is hand the people who own nothing today a real, compounding piece of that growing pie. Sixty years out, the point isn’t that the bottom half finally caught the top. It’s that the bottom half, for the first time, owns something worth owning.

That’s the move the crude “tax the rich” crowd never reaches, because they’re fixated on the pile that exists today. Slice up today’s pile and you get capital flight and a wrecked engine — the whole disaster of the last chapter. Redistribute a modest share of tomorrow’s growth, patiently, and the arithmetic does the work while everyone, top to bottom, comes out ahead in absolute terms. It’s the most win-win redistribution ever proposed, and it only works if you’re willing to be patient — which, over a sixty-year transition, we can afford to be.

The spine: redistribution at death

So where does the redistributed growth come from? The primary source should be the one almost nobody can reasonably object to: death.

When a very large fortune passes at death — past some high threshold, the dynastic-wealth tier, not the family-farm tier — a portion of it converts into Commonwealth shares and is distributed to citizens. That’s the spine of the whole mechanism, for four reasons.

It touches no one while they’re alive. Nobody is forced to sell a company they’re still building or hand over a stake they’re still using. The wealth moves only when its owner no longer can. There is no more painless moment to ask.

It targets the thing almost everyone already finds indefensible. Ask across the political spectrum what kind of wealth is least earned and you’ll hear the same answer: the fortune you were simply born into. A hereditary aristocracy of capital — dynasties compounding across generations who did nothing but be born correctly — is the one form of concentration even hard-core defenders of markets struggle to justify. Redistribution at death aims squarely at that, and leaves the earning and building untouched.

It fits the clock we’re already on. I’ve said from the start this is a sixty-year transition. Here’s the quiet fact that makes death the right lever: the people who own most of the wealth today will be gone within that same sixty years. The transition timeline and the mortality timeline are the same timeline. We don’t have to pry anything out of anyone’s hands. We just decide, now, where the largest fortunes go when their owners are done with them — and then wait, which we were going to do anyway.

And it asks the current rich for something they can actually give: their assent to a rule that costs them nothing in their own lifetime. Some will fight it out of dynastic ambition. But it’s a far easier sell than anything that reaches into a living person’s holdings — you’re not asking them to be poorer, only to let go at the one moment they have no choice but to let go.

And there’s a hard-nosed reason to make this a share conversion rather than just a bigger estate tax: the estate tax we already have barely works. In a recent year it raised only about $18 billion, and touched fewer than one death in a thousand. On paper, the tax takes 40 percent — that’s the top rate the law sets on a fortune passed at death. Almost no one pays anything close. Deductions and exemptions carve down the taxable pile first, so even among the estates big enough to owe anything, the average one hands over about 16 percent of its value. And the very largest fortunes often pay an even smaller share, not a bigger one — because the biggest estates route enormous sums into charity and private foundations, every dollar of which comes off the top, untaxed. The more you have, the more you can give away before the tax ever applies. A 40 percent rate that in practice collects 10 to 16 percent isn’t much of a rate.

Now weigh that against the people it’s aimed at. In a typical year, roughly $60 billion of wealth held above ten billion dollars passes at death — a lumpy number that swings hard from year to year and climbs as today’s biggest fortunes age. At the rate the largest estates actually pay, about 10 percent, the tax collects maybe six billion of it, and much of even that is steered into foundations before it counts. A conversion that took a quarter of that same wealth would capture more than twice as much. The estate tax isn’t failing at the margins; it’s barely touching the fortunes it exists to reach. It’s close to voluntary, because an entire industry exists to route around it. A fortune gets frozen into a grantor trust so its growth passes to the heirs untaxed; it gets parked in a dynasty trust that shelters it for generations; it gets discounted thirty percent or more by wrapping it in a family partnership and claiming the pieces are worth less than the whole; and whatever remains gets the “step-up in basis” at death, which erases a lifetime of capital gains in a single stroke. Something like $13 trillion — a quarter of the top 1%’s wealth — already sits inside trusts built for exactly this. Passing fortunes down untouched isn’t the loophole; it’s the system working as designed.

The Commonwealth conversion closes all of that, at least for the largest estates. It reaches whatever a person owns, wherever they’ve parked it — personal account, dynasty trust, family partnership, private foundation, all the same. There’s no valuation to argue down and no structure to hide behind: it simply takes a fixed percentage of the shares themselves. Own a hundred billion dollars of a company spread across a dozen trusts, and a quarter of those shares still convert to citizens’ hands when you die, no matter how the lawyers labeled them. That the reach includes private foundations matters most, and it’s part of the point. Today a billionaire can pour a fortune into a family foundation, keep effective control of it, pay out the legal five percent a year, and let the rest compound under the family name forever, untouched. The conversion reaches that too: once a fortune crosses the line, a slice of its shares goes to citizens whether it sits in a foundation or not. We are not letting the money slide into a charity to sit. And to be clear about the size of the ask — the conversion takes 25 percent and leaves 75. A founder’s heirs keep three-quarters of a fortune north of ten billion dollars, which is still, by any measure, a dynasty. It isn’t a bigger version of the estate tax that fails; it’s a different tool, aimed at the asset instead of the appraisal, and it can’t be gamed the same way.

The supplement, and why it’s paid in shares

Death is patient, though, and some of the people who can’t wait can’t wait that long either. So alongside the estate spine runs an annual levy — half a percent or one percent a year, the two figures I use throughout — on the wealth a person holds above ten billion dollars.

The most important words in that sentence are paid in shares. Not cash — shares. The billionaire doesn’t write a check; a corresponding slice of their stock transfers, as stock, into citizens’ accounts. This one choice solves three problems at once.

It can’t crater the market, because nothing is being sold. That’s the trap a wealth tax paid in cash falls into: to hand the Treasury a billion dollars, a founder has to sell a billion dollars of stock, and dumping that much onto the market collapses the price of the very thing you’re taxing. Transfer the shares intact and there’s no sale, no dump, no crash.

It needs no buyer. This is the part even the “just make them sell” crowd misses: a forced sale requires someone on the other side with the cash to buy — and there is no pool of buyers big enough to absorb trillions without the price falling through the floor. Transferring shares directly skips the buyer entirely. The stock simply changes owners.

And I should be straight about the objection a budget hawk will raise: the government collects no cash. A normal wealth tax feeds the Treasury. This doesn’t; the value goes straight from the billionaire to the citizen, with the government as nothing but the plumbing. For my purposes that’s a feature: the goal was never to fund the government, it was to make people owners, and routing the value through Washington’s budget is exactly how you’d lose it. But I won’t pretend the fiscal hawks will love it. They’ll see trillions in wealth changing hands and no revenue landing in the Treasury and call it a missed opportunity. My answer is that it was never the government’s opportunity to miss. It’s the citizen’s.

The Commonwealth Account

Where do the shares go? Into an account with the citizen’s own name on it — the same kind of account the newborn’s seed grows in, now holding a grown adult’s redistributed stake. Call it a Commonwealth Account.

A commonwealth is wealth held in common — but read the word again and it’s common wealth, wealth made common by being spread to everyone, one person at a time. That’s the whole distinction between this and every sovereign-wealth-fund proposal on the table. Sanders would pool the shares in one federal fund and let a commission vote them. A commonwealth isn’t a fund; it’s a country full of individual owners. The wealth is common because everyone has some — not because the government holds it on everyone’s behalf. Same instinct, opposite machine, and the name says so.

Two rules make the Commonwealth Account work. First, the shares carry a real pass-through vote — the citizen votes their own stake, the way I laid out earlier; a commonwealth of owners who don’t vote is just a subsidy with extra steps. Second: the shares have to be held.

If a forty-year-old receives a redistributed stake and can sell it Monday morning, most of it flows right back up the mountain — a payday-loan balance, a car repair, and the shares are gone, bought by someone who already had plenty, and the concentration you just fixed re-forms within a decade. So the stake comes with a holding requirement: you own it, you vote it, you collect what it earns, but you can’t sell it for a set stretch of years — and the younger you are, the longer that lock, because you have the most time for it to compound. A clean version: the shares lock for half the years between your age and sixty. A thirty-year-old holds fifteen years, a forty-year-old ten, a fifty-year-old five; a twenty-year-old holds twenty, which is a long time, but a twenty-year-old can afford it. Past retirement age there’s no lock at all, and hardship exceptions cover genuine emergencies. It isn’t paternalism for its own sake. It’s the difference between handing someone an asset and handing someone a windfall that evaporates. The floor has to stick, or it isn’t a floor.

To see how that plays out, picture the whole living cohort seeded in the same launch year — say 2027. Because the lock length is set by age but everyone’s clock starts at once, the oldest come free first and the youngest last:

Age at grantLockupUnlocks at ageUnlock year
505 years552032
457 years522034
4010 years502037
3513 years482040
3015 years452042
2517 years422044
2020 years402047

That stagger is the point, not an accident. If every lock expired in the same year, you’d get a wall of people cashing out at once — selling shares by the millions, knocking down the price of the very thing they hold. Spreading the unlocks across fifteen years means no single-year flood, the same instinct as taking the wealth in shares instead of cash. And it’s gentler still than the table looks, because the real stake doesn’t arrive in one lump — it accrues year after year, as the levy runs and fortunes convert at death, and each year’s shares carry their own lock. The unlocks become a steady trickle rather than any cliff at all.

What it adds up to

Before the numbers, look at who owns what today — it explains why the pool we’re redistributing from is the size it is.

The bottom half of the country owns about one percent of the stock market; the top ten percent own about 87 percent. But “the top ten percent” is not a thousand billionaires. It’s roughly twenty-five million people, everyone from about $1.5 million up to Elon Musk. Pull that group apart and the shape surprises people:

TierRoughly how manyShare of the marketAverage stake
Billionaires (over $1B)~950~10% (~$8T)~$8.4B
Centimillionaires ($100M–$1B)~10,000~4–5% (~$3–4T)~$350M
The merely-rich ($1.5M–$100M)~25 million~72% (~$57T)~$2.3M
Middle 40% (50th–90th percentile)~100 million~12% (~$9T)~$90k
Bottom 50%~125 million~1% (~$0.8T)~$6,400

The billionaires everyone pictures are only about a tenth of the market. The centimillionaires below them add a few more points. The great mass of concentrated stock — nearly three-quarters of the whole market — is held by the merely rich: the twenty-five million people worth between $1.5 million and $100 million. Successful professionals, business owners, executives, retirees with large accounts. Not famous, not billionaires, just comfortable and numerous. Spelled out per head, the gap is the whole subject of this chapter: the bottom half owns about $6,400 of the market each, the merely-rich about $2.3 million, the billionaires about $8 billion. A stake so small it rounds toward nothing — and making it real is what the rest of this chapter is about.

That single fact sets the ceiling on everything below. You cannot make every American rich by taxing billionaires, because there aren’t enough of them: their entire $8 trillion, seized to the last dollar and split across 250 million people, comes to about $32,000 each — once. The real mass of wealth sits in that $1.5-million-to-$100-million band, and reaching it means taxing dentists and family firms — a different and far uglier fight. So this proposal stays at the very top on purpose. It draws its line at ten billion dollars, takes a slice, and accepts that the slice is modest. The engine of the shareholder society was never redistribution — it’s the seed, compounding over a lifetime. Redistribution is only the bridge for the people who can’t wait for that.

Where you draw the line is the biggest dial on the numbers, precisely because of that shape:

  • Above $10 billion — the proposal — is a pool of about $4 trillion.
  • Above $1 billion, all billionaires, is about $7 trillion.
  • Above $100 million, adding the centimillionaire band, is about $11 trillion — enough to roughly triple every figure in the tables below.

Go lower than $100 million and the money finally gets large, but you’re taxing the merely-rich, and the politics turn brutal. The proposal keeps the line high and the ask small, by choice.

Two things to pin down first — who the money goes to, and where it comes from — and then the arithmetic in the open, before any table.

Who gets it. It goes broadly: to everyone outside the wealthiest tenth, call it 250 million adults. (The top 10% already own about 90% of all stock; handing them more misses the point.) The exact line is worth debating; I lean broad. Concentrate it on just the bottom half instead and every figure below roughly doubles.

Where it comes from, and how much. Two separate streams.

The first is death. Roughly $60 billion of wealth above ten billion dollars passes at death in a typical year — and that figure deserves some honesty. It’s lumpy: most years are quieter, but the year a Buffett or a Gates dies, a single estate can swamp the average. It’s rising, as today’s mega-fortunes age. And it’s probably conservative, because much of this wealth is routed to private foundations rather than heirs and the usual transfer figures miss it — but the conversion takes its slice wherever the wealth lands, foundations included, so if anything the real base is larger. Take a quarter of $60 billion, about $15 billion, split among 250 million people, and it comes to only about $60 a person.

The second is a yearly levy. The wealth sitting above ten billion dollars is about $4 trillion. A half-percent levy on it is $20 billion a year — about $80 a person.

Together, roughly $35 billion a year, or about $140 a person: $60 from death, $80 from the levy. Take the levy to its second tier, one percent, and it rises to about $220 a person.

That sounds tiny, and per year it is — deliberately so. Paid in every year and grown at seven percent, $140 a year becomes about $28,000 over a forty-year working life; $220 becomes about $44,000. I won’t dress these up: they stay small. This is the part of the plan that shows the limit of seizing wealth. It goes to the people who came too early for the seed — the adults alive today — and for them a modest bridge is the whole of it. The seed builds the real wealth, but only for the generations young enough to catch it. Every figure in the tables below is just this calculation, run for each starting age. (It all rests on estimates — about $4 trillion above the line, roughly sixty billion passing at death each year (lumpy, and likely conservative), 7% growth — so read the numbers as magnitudes, not precise totals.)

The first stream is the annual levy: a half-percent or one-percent tax each year on the wealth a person holds above ten billion dollars, collected in shares, spread across everyone, and left to grow at seven percent. Here is what it builds in an account by age sixty, on its own:

Age nowLevy 0.5%Levy 1%
20$16,000$32,000
25$11,100$22,100
30$7,600$15,100
35$5,100$10,100
40$3,300$6,600
45$2,000$4,000
50$1,100$2,200

The second stream is the estate conversion: a one-time quarter taken from a fortune above ten billion dollars when its owner dies, drawn from the roughly $60 billion that passes at death each year. Spread and grown the same way, here is what it builds on its own:

Age nowEstate at 25%
20$12,000
25$8,300
30$5,700
35$3,800
40$2,500
45$1,500
50$830

And here are the two streams added together — the whole of what the account holds by sixty, at the base rates and at the second tier:

Age nowBase (0.5% levy + 25% estate)Second tier (1% levy + 25% estate)
20$28,000$44,000
25$19,400$30,400
30$13,200$20,800
35$8,900$13,900
40$5,700$9,000
45$3,500$5,500
50$1,900$3,000

A real floor where there was none — not a fortune, and smallest for those who start middle-aged, but real.

The recipient pool and the threshold are the two dials, both covered above. Drop the line from ten billion to one billion and the base roughly doubles, so these figures would too — a twenty-year-old around $49,000 at the base rate, $78,000 at the second tier — but that reaches down into the smaller billionaires — the $1-to-$10-billion fortunes, still the rich, not the merely-rich — and it isn’t the proposal. Keeping the line at ten billion keeps the ask small and the numbers honest. Which is the real lesson of this whole section: even aimed squarely at the top and left to compound for a lifetime, seizing wealth builds only a modest floor. The fortune-building is the seed’s job. This is the bridge — and a bridge is all it was ever going to be.

What it does and doesn’t do

Newborns get the seed. Future giants get caught by the scale-threshold. And everyone already alive gets a Commonwealth Account — filled over the coming decades by redistribution at death, topped up by the modest annual supplement, and seeded further by handing citizens the stakes the government already holds in companies like Intel rather than keeping them in Washington. Several streams, one account, every citizen an owner.

I won’t oversell it. The forty-year-old will not wake up next year on the newborn’s million-dollar trajectory; they don’t have the runway, and no mechanism can manufacture time. What they get is a real stake that grows for twenty or twenty-five years instead of sixty — smaller, but real, and theirs, and voted by them. And the closer you are to retirement, the more the estate stream and the shorter holding requirement are built to reach you, because you have the least time to wait. It’s a floor that arrives late for the people who are already late, and on schedule for everyone behind them. That isn’t a perfect answer. It’s the honest one, and it beats telling half the country the good idea is for their grandchildren.

The crude approach — seize the fortunes, cut everyone a check — sets off the capital flight and collapse the last chapter described, and still doesn’t add up. This is the other way. It redistributes the growth: at death, in shares, into accounts people own, vote, and can’t quickly cash out — and it leaves everyone, top to bottom, richer than they started. That’s the Commonwealth: how a country split into owners and everyone else slowly becomes a country of owners.

Chapter 4 — Why Not Just Tax the Rich?

listen here on Spotify Instead

The obvious answer, taken seriously

I’ve shown you what I actually want to build — a real ownership stake for every citizen, seeded young and compounded for a lifetime. And I can hear the objection already, because it’s the one that surfaces the instant money is on the table: why go to all that trouble? The top already owns almost everything — so why not just tax the rich and hand it out? I promised back in Chapter 1 that I’d take this reflex head-on. Here it is, stated as strongly as I can make it, because I don’t want to knock down a strawman.

The top 1% own about half of all stocks. The top 10% own nearly 90%. You’ve seen those numbers, and the conclusion writes itself: the money is sitting right there, in a small number of very large piles, so tax it — raise the top rate, add a wealth tax, use the proceeds to lift everyone else. It’s the first thing almost everyone reaches for, across the whole political spectrum, and it has the great virtue of sounding obvious. If a few people have too much, take some of it back.

Here is the snapshot underneath those two numbers — the whole stock market, sliced by how much people own:

TierRoughly how manyShare of the marketAverage stake
Billionaires (over $1B)~950~10% (~$8T)~$8.4B
Centimillionaires ($100M–$1B)~10,000~4–5% (~$3–4T)~$350M
The merely-rich ($1.5M–$100M)~25 million~72% (~$57T)~$2.3M
Middle 40% (50th–90th percentile)~100 million~12% (~$9T)~$90k
Bottom 50%~125 million~1% (~$0.8T)~$6,400

Look at where the weight actually sits. The billionaires everyone pictures own only about a tenth of it. The great bulk — nearly three-quarters — belongs to the twenty-five million merely-rich: successful professionals, business owners, executives, retirees with full accounts. Not a few hundred villains in a penthouse, but a broad, numerous, comfortable class. Hold onto that, because it is going to matter twice before this chapter is done.

I don’t think it works. Not because it’s immoral — we can argue that separately — but because it fails on its own terms, twice over, for two completely different reasons. First, the tax you’d raise doesn’t actually reach the wealth you’re aiming at. Second, even if it did, there isn’t enough of it to do the job. Take those in order.

Reason one: the money you’re taxing isn’t the money you’re mad about

Start with a distinction the whole debate runs on and almost nobody says out loud: income and wealth are different things, and the income tax only touches one of them.

Income is a flow — a paycheck, a salary, money that arrives and gets taxed on the way in. Wealth is a stock — assets you already hold, sitting there, appreciating. The person you’re actually angry about, the founder worth tens of billions, has almost no income in the tax sense. He holds appreciated stock. He can take a $1 salary, borrow against his shares when he needs cash, and never trigger a taxable event at all. The income tax, however high you crank it, sails right past him — because he isn’t earning income. He’s holding wealth.

So when someone says “raise the top income-tax rate on the rich,” the honest question is: which rich? The rate reaches the surgeon making $600,000 and the mid-tier executive making a few million in salary. It barely grazes the billionaire, whose money isn’t structured as income in the first place. You’re aiming a tool built for flows at a mountain of stock.

“But we taxed them at 91% once”

Here’s where someone always brings up the golden age. We used to have a 91% top rate and the country did fine — the rich just paid their share. It’s the strongest-sounding version of the objection, so it’s worth getting right, because the facts cut the other way.

First, a small correction that matters, because slipping on it gets you dismissed: the 91% rate wasn’t the 1970s. It ran from 1951 to 1963, peaking at 92% in ’52 and ’53. Kennedy and Johnson cut it in 1964, and the seventies were actually a 70% decade. “91% in the seventies” is off by a decade and twenty-one points.

More important: almost nobody paid it. Three reasons.

The bracket barely applied. The 91% rate only hit income above $200,000 — roughly $2 million in today’s money. In a country of 150 million people, estimates put the number of households that actually reached it at fewer than ten thousand.

The law capped itself. From 1952 to 1962 a provision limited your total effective rate to 87%, no matter how the brackets stacked. The 91% was never really the ceiling.

And the effective rate was far below the headline. The best data here — Piketty, Saez, and Zucman — finds that across the 1950s the top 1% paid about 42% of their income in all taxes combined: federal, state, local, everything. By 2014 that same group paid about 36%. The “golden age of soaking the rich” moved the actual needle by something like five points versus today.

Why the gap between 91% and 42%? Because the rich did then exactly what they do now — they moved their money into whatever the code taxed least. In the 1950s that meant converting salary into capital gains. Actors and directors were the pioneers; the LA Times called it “the golden age of tax avoidance.” Cecil B. DeMille set up a personal corporation that “sold” his services, paid the lower corporate rate, and drew a modest salary on top. The mechanism has a hundred names across the decades — loan-out corporations, collapsible corporations, stock options, and finally just never selling — but it’s always the same move. Money flows to the lowest rate. Raise the rate on one channel and it finds another. The 91% didn’t soak the rich. It taught them to swim.

The cleanest proof: what happened to CEO pay

If you want to watch this happen in slow motion, with a paper trail, look at executive pay — because we ran the experiment on purpose and it backfired in the most instructive way possible.

In 1993, Congress tried to rein in CEO pay by capping the corporate tax deduction for executive salary at $1 million. The intent was obvious: make it expensive to pay a boss more than a million in salary, and salaries will come down. Instead, pay didn’t shrink — it changed species. Boards shifted compensation out of salary, which was now capped, and into stock and options, which weren’t. Look at any big public company today and you see the fingerprint. Ford’s CEO, GM’s CEO: base salaries around $2 million, and then twenty-plus million more in equity on top. The salary is a rounding error on the package.

Meta is the purest illustration. Mark Zuckerberg takes a $1 salary and no stock grants at all — he doesn’t need them; he already owns the company. His reported “compensation” is essentially the cost of his security detail and his plane. His real wealth is founder’s stock he simply holds and never sells. He is the billionaire from two sections ago, wearing the CEO costume: the income tax has nothing to grab.

(While we’re here — the “CEO-to-worker pay ratio” quoted in every article is three different numbers wearing one name. The per-company SEC figure divides the CEO by the company’s global median worker, so a firm with big overseas factories posts a monstrous ratio for reasons that have nothing to do with the boss — Mattel’s 2,152-to-1 is really a map of where its factory workers live. The famous “20-to-1 in 1965, 281-to-1 today” trend measures something else again, and the British version divides by the national median. Three rulers, three numbers, one debate that mostly doesn’t notice. A bad thermometer for a real fever.)

The real point is the one this whole chapter is building. CEO pay went from salary — income, taxed heavily and now — to equity — a claim on appreciation, taxed lightly and later. We built a rule specifically to shrink it, and instead we taught it to grow in the one form the income tax can’t follow. The organization man of 1958 was cheap because the code left him no reason to be expensive. Today’s executive is expensive because the code handed him a better vehicle. Same physics. Different decade.

What actually restrains the rich — and it isn’t the tax code

Here’s the part I have to be honest about, because it cuts slightly against my own argument, and I’d rather raise it than have you catch me hiding it.

Plenty of rich countries pay their executives a fraction of what America does — a third to a half in Europe, about a fifth in Japan. So something restrains pay elsewhere. And the tell is that it isn’t the tax code. American base salaries are actually lower than Europe’s; the entire American premium is equity. And the high-tax countries — France, Denmark — don’t have modest CEO pay because of their taxes. They have it because of governance and culture. Germany puts workers on the board and lets them vote on pay. France and Brazil make the shareholder vote binding. India caps board pay by law. Japan shames it through disclosure. Denmark pegs the boss’s raise to the workers’. None of that is a tax.

So here’s the honest shape of it. Tax explains the American trajectory — the 1993 cap, the flight into equity, the whole slow migration this chapter traced. But governance and norms explain the cross-country levels. Two things are true at once, and I need you to hold both: taxing income can’t reach modern wealth — that’s the spine of my argument, and the equity migration proves it — but the tools that do restrain concentration are ones America mostly doesn’t use, and they’re structural, not confiscatory. Hold that second thought. It comes back when we get to the vote, because it turns out the fix was never to take the shares. It was to change who holds and votes them.

Reason two: even if you could reach it, there isn’t enough

Set all of that aside for a second. Suppose you could tax wealth directly — reach the founder’s stock, the appreciated assets, the whole pile. Grant yourself the tool the income tax doesn’t give you. It still doesn’t work, because the pile isn’t big enough to do what people imagine.

The figures here are from 2025 and they’ll drift — but the magnitude is the point, and the magnitude is what settles it.

There are around 935 billionaires in America, holding something like $8 trillion between them. That sounds like an ocean until you set it beside the thing people want it to pay for. The federal government spends about $7 trillion a year and runs a deficit — the annual gap between spending and revenue — of roughly $1.85 trillion. So the entire combined wealth of every American billionaire, seized in full, covers about one year of the deficit. Not the debt. The deficit. And the next year the deficit is back, and the billionaires are gone.

Run it as a recurring tax instead of a one-time seizure and it gets worse. To cover just the deficit — not to fund anything new, only to close the annual gap — you’d have to take about 23% of all billionaire wealth every year, forever. That’s not a tax; it’s a liquidation. And it can’t physically happen: you can’t sell a quarter of the country’s concentrated equity every year without collapsing the price of the thing you’re selling, and the moment you try, the capital moves. Norway raised its wealth tax and watched a wave of its wealthiest residents decamp to Switzerland, taking their tax base with them — the same capital flight that helped push France to scrap its wealth tax altogether.

And notice how far this is from what the serious proposals even ask. The academic wealth-tax plans — Piketty around 5 to 10%, Saez and Zucman around 10% — are a fraction of the 23% the deficit math alone demands. The most ambitious real proposals on the table don’t come close to closing the gap, and they’re already well beyond what’s politically or practically achievable.

There are really two different things people mean by “tax the billionaires,” and neither works. If the goal is revenue — money to fund things — the pile is too small and too illiquid: a year of deficit, then gone. If the goal is leveling — closing the gap itself — I showed you in Chapter 1 that the bill for putting every adult on a decent footing runs to $63–94 trillion, bigger than the entire stock market. You cannot get there by moving around the $8 trillion at the top. Revenue or leveling, the number at the top is a distraction from the number that actually decides it.

So where does that leave us

Put the chapter together and the reflex fails from every direction at once. Raise the income tax and it misses the wealth, which isn’t income. Reach back to the 91% golden age and find that no one paid it — the money just changed vehicles. Point to the countries that actually restrain concentration and find they do it through governance, not seizure. Try to confiscate the pile directly and find it’s a single year of deficit that craters and flees the moment you grab for it.

None of this means the concentration is fine. It means the tool everyone reaches for is the wrong one — aimed at a flow when the problem is a stock, sized for an ocean when the pile is a pond. The honest conclusion isn’t “leave it alone.” It’s that you don’t fix a shortage of ownership at the bottom by seizing ownership at the top. There isn’t enough there, it won’t stay put, and you’d wreck the engine grabbing for it.

Which turns the whole question around. If you can’t get people a stake by taking one, the only move left is to build one. That’s the rest of the book — and it starts with the lever that does the thing the tax code can’t: it puts real, appreciating, wealth-type ownership into ordinary hands, instead of chasing it around the code after the fact.

Chapter 3 – A Shareholder Society – The Ownership Lever

Listen on Spotify Here

This is chapter 3 of a set of ideas I’m putting together that may (or may not) end up as a short book, pamphlet etc. I am continually trying to understand how to make the world a better place. This is one set of proposals. I’m happy to hear feedback! Please share. If you are able, start to engage in sharing your wealth with others. You can start with your family, but you can then branch out to others!

What the seed actually becomes

The last chapter ended on a question: what would it take to carry every newborn from a single seed all the way to a real retirement? Here’s the answer, and it’s smaller than you’d guess.

Eighteen thousand dollars, invested once at birth and then left completely alone, grows to about $1 million in today’s dollars over sixty years. One deposit. Nothing added after it. No discipline required, no dependence on whether the parents could spare a cent. Seven percent above inflation — roughly what U.S. stocks have delivered over the long run — compounded across six decades turns eighteen thousand dollars into a million in real purchasing power.

I use $18,000 as the do-the-whole-job number — the top of the range, the deposit that fully funds a millionaire outcome from a single seed.

About 3.6 million babies are born in this country each year. At $18,000 apiece, seeding every one of them runs about $65 billion a year. Set that against a federal budget of roughly $7 trillion and it’s under 1% of what the government already spends. The maximum version of this idea — every newborn on track to a real million — costs less than a penny on the federal dollar.

And we already run a miniature version. The Trump Accounts seed every citizen newborn with $1,000 in a low-cost index fund. That $1,000, left alone at 7% real, becomes about $58,000 in today’s dollars by retirement — which, remarkably, is more than the typical American saves in an entire working life. Not because $1,000 is a lot, but because it gets sixty uninterrupted years and most people never give themselves that. The last chapter’s tables showed the same thing from the other direction: the young are absurdly cheap to fund and the old break the bank, and the whole difference is compounding. Time does the heavy lifting, and the young have all of it.

So the mechanism is right; the size is wrong and fixable. The harder question isn’t how much — it’s why this at all. Why ownership, not just a better wage or a monthly check?

The floor most people stand on is a wall

To see why a share beats a wage, you have to be honest about what a wage actually is.

Take ordinary work — driving a bus, picking a warehouse order, running a register, answering a support line. This work has real value; a city without bus drivers is worse off, and so are the people who couldn’t get to their jobs. But the value isn’t scarce. Lots of people can do it. And a price is set by scarcity, not by usefulness. So why does the Swedish bus driver earn a Swedish wage instead of an Indian one, for the identical task? Because a border and a license keep the person in India from showing up and doing the job for half the pay. If that person could simply come and drive the bus, the wage would fall to meet them.

That border is a wall. It holds a price up by keeping the cheaper competitor out — and it’s been running the whole time, long before anyone mentioned AI. Half the wages in the developed world are propped, to some degree, by a wall that keeps a willing, lower-priced worker on the other side of a line.

There’s a cruel version of this point and a true one, and only the true one is mine. The cruel version is “most people add no value.” That’s false. The true version is narrower: the value is not scarce. The wage measures scarcity, not worth. The entire humane core of this project is the claim that a person’s worth is not their market price.

So the wage floor was always a propped one. Here’s why AI is different from every earlier wave of cheaper labor, when “someone will do it cheaper” is the oldest story in economics: for the first time, the cheaper competitor is on the inside of the wall. You can keep a foreign worker out with a visa. You cannot keep a model out with a visa. It needs no work permit, crosses no border, and lives in a data center down the road. The wall that held the wage up does nothing against it. And a propped floor doesn’t sag gently when the prop goes — it holds, and holds, and then fails all at once.

The only floor that doesn’t need a wall

Here’s the whole case for the shareholder society in a single contrast.

Every floor built on a wage needs a wall to hold it up — a border, a license, a union rule, a tariff, an occupational cartel. Walls are politically fragile; they’re one election or one trade deal from coming down. And against AI they’re not even fragile, they’re useless, because the competitor is already inside.

A floor built on a share needs no wall at all. A share’s value doesn’t depend on keeping any competitor out. It’s a claim on production however cheaply that production gets done — and it gets stronger as production gets cheaper. The same AI that destroys the wage increases the profit, and the shareholder owns the profit. Ownership is the one floor that rises as labor gets cheaper instead of collapsing with it. The thing that kills the wage feeds the owner.

You can already watch people reach for the wall anyway. Bernie Sanders has called for a moratorium on new AI data centers and a pause on advanced AI development, to protect workers from mass job loss — a wall thrown up against the machine itself. I understand the impulse, but it doesn’t work, and not only because the competitor is already inside. It’s that this particular wall can’t be built by one country. Slow AI down in America and you don’t stop it — you hand the lead to the countries that don’t, and they out-compete us with the very tools we refused to build. You can wall a cheaper worker out at the border. You cannot wall out a technology the rest of the world is racing to develop. Which is the deepest reason to prefer a share to a wall: a share lets ordinary people win from the machine’s advance, instead of staking their floor on a doomed attempt to hold it back. (Sanders, as it happens, has the ownership instinct too — he just builds it the wrong way, which I’ll come to.)

It’s the structural reason a stake beats every alternative on offer. A UBI is a wall made of tax policy — one budget fight from shrinking. A protected job is a wall made of licensing — one disruption from falling. A closed border is a wall made of law — one election from opening. A share is not a wall. It’s a piece of the thing itself. That’s the difference between handing someone a check the government has to keep choosing to write, and handing them an asset they own outright. If your labor isn’t needed, your shares are how you eat — and, once they carry a vote, how you’re heard.

And there’s a benefit here that runs deeper than the income — one I’ll come back to at the end of the book. A check keeps you a recipient, a spectator of an economy that merely happens to you; a share you own and vote makes you a participant in it. People who own begin to think like owners, and that change in how a person stands toward the whole system is a large part of what the system is for.

“But that’s unearned”

The standard objection arrives right here: people should earn their stake through work. You don’t just hand out shares. That’s unearned.

The answer falls straight out of the wall. The well-paid worker’s premium was already unearned — a wall-protected rent, not a reward for scarce value. The Swedish wage paid over the Indian wage for the identical task is a transfer the state is already choosing to make, through immigration and licensing law, in favor of whoever was born inside the wall. Society already redistributes to people whose labor isn’t globally scarce. It just launders the redistribution through a wage and a border so it looks like earnings.

So “unearned” isn’t a line that separates a shareholder stake from the status quo. Unearned is the status quo. Universal ownership doesn’t inject redistribution into a pure meritocracy — it takes a redistribution we’re already running behind a wall and does it in the open, as a share you own and vote, portable and not contingent on holding a protected job. And unlike the wall, the share doesn’t vanish the moment the politics shift or the model shows up. It’s the more honest version of a transfer we’re already making, and the more durable one. I’d rather hand someone a share they own than a wage I have to keep a wall standing to protect.

Keep the machine ownable

Everything so far assumes one thing: that the productive economy is ownable — public, listed, reachable by an index fund and a seed account. That’s the bolt the whole design rests on, and it’s starting to shear, three ways at once, each one pulling the best part of the economy out of ordinary reach.

It’s going private. The number of public U.S. companies is about half what it was in the mid-1990s, and companies now do their steepest growth while private. The frontier AI labs — the sharpest edge of the whole economy — are private. By the time a modern company reaches your index fund, the fast part is over; you’re buying the plateau. And the richest compounding is walled off deliberately: to buy into most private companies you need about $200,000 of income or $1 million in net worth. Read that plainly — you’re allowed to own the fast-growing part of America only after you’re already rich. That’s the same captured-rule mechanism as the zoning that keeps housing expensive, just naked: a wealth test on entry to the best returns.

It’s getting lean, and at the limit, solo. The endpoint everyone flinches from is the founder who builds something at the scale of a major lab using AI agents — raising no outside capital, issuing no shares, hiring no one. Walk that company through both of the ways value normally reaches people and watch them run dry at once: no employees means no wages flowing into any community, and no shares ever sold means nothing on a cap table for a citizen fund or a seed account to buy. It’s the one structure where both levers fail together. The small version already exists — the solo operator with an automation stack. The trillion-dollar version is maybe fifteen or twenty years out. Worth building the framework to survive it before we need it.

Concentrated ownership doesn’t only decide who gets to buy — it decides what gets built. If demand tracks ownership and ownership is top-heavy, the automated economy optimizes for what the owners want: the yacht, not the cheap house, because the yacht is where the spendable money is. Broaden the ownership and you broaden the demand signal — you keep the machine’s attention on the mass-market goods that reach everyone. Universal ownership isn’t only how the poor get an income. It’s how the economy stays interested in serving the poor at all.

So the fix has to keep the machine ownable without becoming the confiscation I ruled out. Here’s the shape. Any company that grows past some very large scale — think a trillion dollars in value, and maybe far more — has to issue a slice of itself into citizens’ own accounts, carrying a real pass-through vote. The size of that slice could scale with the size of the company. I’m deliberately not naming the threshold or the percentage; those are dials for public debate. What I’m putting forward is the framework, not the settings. It’s a condition of operating at civilization scale, published in advance, in the same category as a listing requirement or a tax bracket. Even a one-person company that never sold a share, once it crosses the line, mints equity into the citizen vehicle. Whether the founder is paid for the slice or simply diluted to make room is exactly the kind of thing public debate should settle — I’d put both on the table.

Why isn’t that the seizure I swore off? Three reasons. It’s prospective and known — I’m setting the price of a new tier of scale before anyone reaches it, so every founder builds knowing the deal; that’s a rule of the game, not a taking. It’s built on the public’s own custom — a company only reaches this scale by serving hundreds of millions of people, and the valuation just is that ongoing custom capitalized into a number. And it’s rent on the commons — nobody builds a colossus on bare ground; they build it on courts that enforce their contracts, on publicly funded research their models descend from, on infrastructure and education and a stability that guards their property while they sleep. The citizen stake is the public collecting on infrastructure it already provided.

It’s worth measuring all this against the most prominent version of the same instinct — because someone got there first, and where we agree matters as much as where we don’t. Bernie Sanders’s 2026 American AI Sovereign Wealth Fund Act would take a one-time 50% stock tax on the largest AI companies, pool the shares in a federal fund, and pay every American a yearly dividend. On the goal, he and I want the same thing: the public owning a real piece of the productive machine, and I take it as good news that the idea has reached the floor of the Senate.

And it isn’t only Sanders, or only the left. The Trump administration has already taken direct equity stakes in a string of companies — about 10% of Intel, 15% of the rare-earth miner MP Materials, pieces of several others — a government portfolio one of its own economic advisers called “a down payment on a sovereign wealth fund.” So the machine passing into public hands is neither hypothetical nor partisan anymore; it’s arriving from both directions at once — seize-it-into-a-fund on the left, take-a-strategic-stake on the right. Which sharpens the whole thing to a single question: it was never whether the public comes to own a piece of the economy, but who holds that piece and who votes it — a Washington fund, or the citizen. And that is where I part from both of them, because the design is everything. (What should be done with the stakes Washington is already piling up, I’ll pick back up when I reach the people the seed can’t help.)

Start with the amount. He takes half in a single move, where I’d start with a sliver at a far higher bar and let it grow slowly, if at all — because 50% at once isn’t broadening ownership, it’s nationalizing an industry. Then the scope, where the difference flips: he socializes only the biggest AI firms, while the shareholder society is about the whole productive economy — every company, reached through the broad index the seed accounts already buy. His is deep but narrow, half of a handful of companies; mine is shallow but broad, a small piece of everything.

Third — and this is the real fault line — who ends up holding the power. Sanders’s bill routes the public’s stake through an Independent Commission for Democratic AI: seven presidential appointees who manage the fund “in the public interest” and vote its shares to block what they judge harmful and push what they judge helpful. Read that plainly. It’s a new arm of government that decides, on your behalf, what the public interest is. That’s more government, not less — the state owning the machine and a handful of appointees steering it. My whole design is the opposite move: don’t build a commission to hold the shares and cast the votes for three hundred million people — give the three hundred million people the shares, and the votes, directly. A stake in your own account. A ballot you cast yourself. He’d call his commission “democratic”; I’d point out that seven appointees voting the nation’s shares is representation at best, and that the more genuinely democratic thing is for every citizen to vote the piece they actually own. Same word. Opposite machine.

There’s an honesty I owe on my own side, though. His bill simply seizes — “we’re not buying it,” as he put it, “we’re getting it” — half of companies already built, which is the retroactive taking I ruled out and the reason it’s already drawing constitutional fire. My going-forward pieces avoid that by being prospective. But I haven’t solved the mirror problem for the companies that already exist and the adults who already do: my instinct runs the opposite way from his — buy the shares at fair value and hand them to people rather than seize them — but buying costs money, and that lands us right back on the hardest question in this book, the one I keep promising to face. I’d rather name that gap than paper over it.

And that thread — start small, keep it individual, buy rather than seize — is also the answer to the worry that any program like this only ratchets upward over time. Of course it does; the income tax began as a levy on the top 1% and now reaches nearly everyone. But the question was never whether the stake grows, it’s what grows. If a government fund’s share of the economy ratchets up, that’s the state accumulating control. If individual citizens’ ownership ratchets up, that’s ordinary people accumulating power over their own lives. Same direction of travel. Opposite destination.

The vote

I keep saying “a share with a vote,” and I mean it as load-bearing, not decoration. Ownership without governance is just a dividend check, and in an economy increasingly run by machines, whoever votes the shares runs everything. So the vote has to reach the actual citizen.

The mechanics are grade-school arithmetic. If you hold $100,000 in an index fund and that fund keeps 8% of its money in Nvidia, you own $8,000 of Nvidia — so you should vote $8,000 worth of Nvidia shares. Your ownership looks through the fund to the companies underneath, and your vote looks through right along with it, in exact proportion to what you hold. Brokerages already track ownership down to the share; the plumbing exists. Today that vote gets swallowed by a handful of giant asset managers who cast the proxies on everyone’s behalf — a real concentration of power, and the exact thing pass-through voting dissolves. The full case for why the vote matters this much — what it does to a person, and to a democracy — is its own chapter later. For now, hold the principle: your money’s already there; the vote should follow it.

What it costs, and who pays

Pull the money back into view. Seeding every newborn at $18,000 runs about $65 billion a year — under 1% of the budget. But the budget isn’t even the right yardstick. The right comparison is the retirement promise we’ve already made and haven’t funded: Social Security’s unfunded obligation runs to roughly $29 trillion over the next 75 years, its trust fund is projected to run dry around 2033, and benefits get automatically cut by about a quarter when it does. That’s an unfunded, pay-as-you-go promise — today’s taxes paying today’s benefits, the shortfall shoved onto tomorrow’s workers. A seed account is the opposite kind of obligation: pre-funded and compounding, a real asset that grows on its own and eventually needs nobody to tax. It’s the same move private employers already made a generation ago — from the defined-benefit pension, an unfunded promise to pay you later, to the defined-contribution 401(k), a real account you own that compounds on its own. We’d be making that shift for the retirement floor itself: from a defined benefit the country never funded to a defined contribution that funds itself. We’re already standing in a $29 trillion hole; $65 billion a year to build that self-funding stake beside it is a rounding error by comparison.

Which means you’re already asking the obvious question: if it’s so cheap, why not just tax the rich to cover it — or to fund everyone, not only the newborns? Hold that thought, because it’s the whole of the next chapter. The short version is that it doesn’t work, and it’s worth taking slowly.

And I won’t pretend the seed does everything. It rescues the young precisely because it buys them sixty years of compounding — which is exactly why it does almost nothing for the person who’s fifty-five right now, with ten years left and no time for a small stake to grow into a large one. Funding today’s middle-aged is the hard transition problem no seed can solve, and I’ll face it head-on rather than wave it away, later in the book.

But the destination is clean, and it’s cheap for everyone we can still start the clock for. Let the machine do everything. Let one person run a company the size of a nation’s economy if the technology allows it. The fight was never man against machine. It’s over a single question: who owns the machine, and who votes it? Make sure that when it finally needs almost no one to run it, almost everyone still owns a piece — and still gets a say in what it builds.

Chapter 2 – A Shareholder Society – The Floor

Listen on Spotify Here

This is chapter 2 of a set of ideas I’m putting together that may (or may not) end up as a short book, pamphlet etc. I am continually trying to understand how to make the world a better place. This is one set of proposals. I’m happy to hear feedback! Please share. If you are able, start to engage in sharing your wealth with others. You can start with your family, but you can then branch out to others!

The Floor

The number almost nobody has

The first step is a number, and it reframes everything that follows.

The U.S. stock market is worth somewhere around $75 trillion. There are about 255 million adult citizens in this country. Divide the one by the other and you get a little under $300,000 apiece.

That is every adult’s even share of American business — not income, equity. A claim on the machines, the brands, the buildings, the software, and the future profits of the entire economy. Sit with it for a second, because it’s a real number. Then sit with the part that should stop you cold: almost nobody has anything close to it.

That $300,000 is a mean — the whole pie divided by all of us. It is not what the typical person holds, because the pie isn’t split anything like evenly. The top 10% of households own about 87% of all stocks. The top 1% alone own about half of all equities — more than the entire bottom 90% combined. The bottom 50% of Americans own roughly 1% of stocks. And ownership isn’t even that widespread to begin with: only about 58% of adults own any stock at all, and that number recently ticked down. The median household holds around $39,000 in financial assets outside their home. Counting everyone, the median retirement savings across all households is closer to $27,000.

So the average adult’s fair share of the market is $300,000, and the typical person’s actual share is a small fraction of that.

That gap — between the mean and the reality — is where this book starts. But it isn’t what the book is about. Closing it by shrinking the top doesn’t work, as we’ll see, and I’m not much interested in the gap for its own sake anyway. What the book is about is the other way to close it: a shareholder society, where every citizen owns a real, voting piece of the productive economy. And it’s about what that does — not only to the numbers, but to the people who become owners, and to the society they build once they are. The gap is the symptom. The shareholder society is the subject.

The floor, not the gap

I want to be careful about what that gap is and isn’t, because this is where most people take the argument somewhere I don’t want it to go.

The obvious reaction to “the top owns almost everything” is: take some of it back and hand it out. That is not the engine of this book, and I’ll spend a whole chapter later on why the crude version — seize the existing fortunes, cut everyone a check — doesn’t even work. I’ll also be honest, up front, that what I end up proposing isn’t zero redistribution. There’s some in it. But it’s redistribution done a particular way — forward, through ownership rather than a handout, and built slowly — and it’s a means, not the point. The point is the floor.

The right question was never “how big is the gap.” It’s “is the person at the bottom getting access to more over time — a roof, clean water, transportation, energy, care, the next useful thing?” If the floor keeps rising, the gap can stay wide and I’m fine with it. Inequality of outcome at the top is the price of a system that keeps inventing things. Inequality of access at the bottom is the thing worth attacking.

So this is not a book about flattening anything. It’s a book about the floor — how high it is, what holds it down, and how you raise it.

Floor = income ÷ cost

Let me say plainly what “the floor” even is, because I’ll use the word on every page. The floor is not a dollar amount in an account. It’s access — to the things that make a life better. A roof over your head, water you can drink, a way to get to work, power, medicine, schooling, and whatever the next useful thing turns out to be. When I say the floor rises, I mean an ordinary person can reach more of those things than they could before. That’s the whole target. Everything else is machinery for hitting it.

And the livability of that floor is a fraction:

Floor = income ÷ cost of living.

Two levers, not one. You raise the floor by pushing on either term — raise what a person can claim, or lower what living costs — and if you do both they multiply. A modest stake in a cheap world beats a big stake in an expensive one. Almost everything in this book is either about getting each person wealthier or making the things they need cheaper.

Here’s the trap you have to see before any of it works, though. You cannot just raise the income side by handing people money and expect the floor to rise. If a lot of people suddenly have more to spend, they spend it on the same things everyone else is chasing — housing, care, the daily necessities — and the extra dollars just bid the prices up. Cost climbs to swallow the raise. That’s demand-pull inflation, and it’s the reason a sudden transfer mostly reprices the floor instead of raising it.

Which is why the two levers aren’t really independent, and why this has to happen gradually. You have to expand people’s ability to buy and expand what gets produced, so the new demand is met by new supply instead of by higher prices. The market can do that supply response — building the housing, training the caregivers, standing up the production — but it takes time. So the honest version of this project isn’t a switch you flip. It’s a build you pace, over years, so purchasing power and production rise together. Move too fast on the money alone and you inflate the very floor you’re trying to raise.

You can’t slice your way there

Before I get to the two levers, I have to kill the reflex — because if I don’t, you’ll spend the whole book waiting for me to just say “tax the rich,” and half of you will stop listening when I don’t.

So let me put a number on why dividing up what already exists can’t do this job. Pick a genuinely livable retirement stake — enough that, with Social Security, a person clears somewhere around $44,000 to $54,000 a year. Work backward to what every adult would need to hold today to compound to that by 65, band by band, and add it up.

Here’s the fuller version — a $750,000 stake at 65, which throws off about $30,000 a year at a safe withdrawal rate, or roughly $54,000 with Social Security:

Age bandAdultsStake needed / personYears to growCost of the band
18–2431.6M$38,200~44$1.2T
25–3448.4M$70,200~35$3.4T
35–4445.9M$138,200~25$6.3T
45–5442.4M$271,800~15$11.5T
55–6445.2M$534,600~5$24.2T
65–7436.7M$750,0000$27.5T
75+26.8M$750,0000$20.1T
Total277M——$94.3T

Look at the total: $94.3 trillion. The entire U.S. stock market is about $75 trillion. So at this target you cannot get there by dividing up what already exists — the bill is bigger than the whole pie.

Run it leaner, at a $500,000 target (about $20,000 a year from the portfolio, roughly $44,000 with Social Security):

Age bandStake needed / personCost of the band
18–24$25,500$0.8T
25–34$46,800$2.3T
35–44$92,100$4.2T
45–54$181,200$7.7T
55–64$356,400$16.1T
65–74$500,000$18.4T
75+$500,000$13.4T
Total—$62.8T

At $500,000 the whole thing costs about $62.8 trillion, which does fit inside $75 trillion. But notice what “fitting” would mean if you did it by confiscation: you’d be handing over about 84% of the entire stock market — and even that wouldn’t produce equality, because the 16% left over would still sit mostly with the people at the top.

So confiscation fails twice over: there isn’t enough to go around, and the moment you start seizing built companies you kill the thing that makes the pie grow in the first place. (And that’s before you even get to the inflation problem from a page ago — dumping that much purchasing power into the economy at once would reprice everything anyway.) This is the point I’ve been making since 2018, now with a number attached: you cannot slice your way to a floor. The pie has to grow, and everyone has to get a real piece of the growth.

That’s the line between this book and every “tax the billionaires” plan you’ve heard. I’m not trying to redistribute the wealth that exists — not as the main move. I’m trying to build ownership that doesn’t yet. I’ll admit there’s a little redistribution laced through what follows, and I won’t pretend it away; the honest question is never whether but how. And the cleanest, fairest, cheapest place to start is with the people who hold the one thing that turns a small stake into a large one: time. It starts with the young. How far it can reach the people already in the middle of their working lives — the ones without decades left to compound — is the genuinely hard part, and I’ll come back to it rather than wave it away.

The map

Everything else fits into six points. Think of them as the argument in miniature, and the rest of the chapters as each one worked out in full.

  1. The measure is the floor, not the gap. Success is the bottom’s absolute access rising over time. The ceiling can do what it likes.
  2. Floor = income ÷ cost. Two levers, moved together and gradually — because raising claims without raising production just bids up prices. Everything else raises income or lowers cost.
  3. Lower the cost of living through disruption. New things reach the poor by competing against non-consumption — Clayton Christensen’s term for serving people who were priced out entirely, at a price point that didn’t exist before. That’s how anyone gets their first car, their first anything.
  4. Where prices won’t fall, something is blocking them. When a necessity stays expensive for decades, the cause is almost always a captured rule — zoning, licensing, a credential monopoly — not physics. Find the constraint, remove it.
  5. Raise what people can claim through universal ownership. As automation thins out wages, a share replaces the paycheck as the ordinary person’s claim on what the machine produces. If your labor isn’t needed, your shares are how you eat.
  6. The shares have to carry a real vote. Ownership without governance is just a dividend check. Whoever votes the shares runs the economy — so the vote has to reach the actual citizen.

Points 3 and 4 are the cost lever, and they get their own chapter. Point 5 is the ownership lever, and it gets the most argument of all, because it’s the one that has to survive a world where the machine needs almost no one to run it. Point 6, the vote, turns out to matter far more than a footnote about corporate governance, and it gets its own treatment too. Points 1 and 2 are this chapter: watch the floor, and remember it’s a fraction.

Where we go from here

One fraction, two levers, a rule against the shortcut, and a promise to move at a pace that builds supply instead of just bidding up prices. That’s the frame.

The rest of the book is the levers. First, the ownership stake — a real, voting share for every citizen, why it’s the only floor that doesn’t need a wall to hold it up, and how you keep the machine ownable while it tries three different ways to slip out of reach. Then the cost side — driving the price of the necessities that actually decide a life down until they reach the people fancy never could. And underneath both, the question I’ll save for last but never lose sight of: what is the floor actually for? Because the deepest claim in this book isn’t about money at all. It’s that making an ordinary person a real owner — one with a vote — changes how they stand in the world, and changes the society built out of people who stand that way.

The $1,000 the government now seeds into every newborn’s account is a genuinely good start — the mechanism is right, and it proves the country can actually do this. So let’s see what it would take to carry every newborn from that seed all the way to a successful retirement.

Chapter 1 – A Shareholder Society – What the Floor Is For

Listen on Spotify Here

This is chapter 1 of a set of ideas I’m putting together that may (or may not) end up as a short book, pamphlet etc. I am continually trying to understand how to make the world a better place. This is one set of proposals. I’m happy to hear feedback! Please share. If you are able, start to engage in sharing your wealth with others. You can start with your family, but you can then branch out to others!

The point was never the money

Every fix anyone proposes for a hard life comes down to the same two words: more money. Raise the wage, cut the cost, send a check, put more dollars in more pockets. Say it out loud and it sounds not just correct but obvious — of course more money is better, of course cheaper is better. It’s about the only thing the left and the right agree on; they just fight over how.

And for a lot of people, it’s exactly right — I won’t wave that away. If you’re lurching from one bill to the next, more money isn’t a distraction from the good life; it’s the difference between drowning and breathing, and a huge part of raising the floor is simply getting people out of that scramble. For them, another dollar is the whole game, and this book takes that seriously.

But it stops being the whole story sooner than we admit. Past the point where scarcity no longer runs your day, another dollar does less and less to how a life actually feels. The returns don’t vanish — but they diminish, fast. Money keeps helping; it just stops being the thing itself. Once the scramble is over, what it’s really buying is something underneath it.

What actually decides whether a life feels livable is three things money can only buy the conditions for:

  • Security — not how much you make, but whether you can count on it.
  • Agency — a say in how your life goes, instead of being something the world merely happens to.
  • Dignity — a place that still needs you, a standing that doesn’t hang on charity.

A life you can count on, a say in how it goes, and a spot that’s yours. Those three are the goal. More money is only worth having because it can buy them — and if you lose sight of that, you end up chasing the number instead of the life. I don’t want to be one more person promising you a bigger number. I want to talk about the three things the number was always for.

So before any of the machinery — and there’s a lot of it coming — I want to be clear about the target. The floor I’ll spend this whole book trying to raise was never a dollar amount in an account. It’s security, agency, and dignity. Everything else is worth building only to the degree it delivers those three.

Owners think differently

Here is the claim the whole book rests on, and it isn’t really an economic claim at all. It’s a claim about how a person stands in the world.

A wage-earner and an owner look at the very same economy and see two different things. To the wage-earner, the economy is weather — something that happens to them, that they survive or don’t. To the owner, it’s something they have a stake in and a claim on. Watch what happens when the machine gets more productive. The wage-earner braces, because productivity is the thing that comes for jobs. The owner benefits, because productivity is the thing that grows what he owns. Same event. Opposite stance. One person flinches at the future; the other is invested in it.

That difference — from standing subject to the economy to standing inside it — is worth more than most of the dollars, because it is what the dollars were always supposed to buy. It’s agency. And you don’t get it by being handed money. You get it by being made an owner.

This is why I lean so hard on the word “owner,” and won’t take a substitute that merely mimics the cash. A person who owns real shares in the economy — an actual piece of the companies around them — reads the news differently, plans differently, stands differently. Not because anyone lectured them into it — you cannot nag a person into thinking like an owner — but because we made them one, and the stance follows the standing.

Why not just send everyone a check?

Which brings me to the idea nearly everyone reaches for once they finally admit the old floor is failing: a universal basic income. As work gets automated and the wage stops holding people up, the reflexive fix is a check — a monthly payment from the government to every citizen. I understand the appeal. At least it takes the problem seriously.

But a check is just money again — and worse, money aimed at exactly the wrong target. A UBI hands you dollars and leaves you a recipient: a spectator of an economy that happens to you, now holding an allowance the government has to keep choosing to write, and can shrink or cancel the moment the politics turn. It treats the symptom — no income — while cementing the very thing that makes the modern economy feel unlivable: that you stand outside it, dependent on it, with no claim and no say. It hands you a bigger number and calls it empowerment. It’s a subsidy with extra steps.

A shareholder society is the other answer. Not a check — a stake. Not an allowance the state grants, but a piece of the productive economy you actually own and get to vote. The difference isn’t the size of the dollar; it’s what the dollar is. One keeps you a dependent. The other makes you an owner. This entire book is an argument that we should replace the check we’re drifting toward with a share — that the answer to a failing wage floor is not to turn people into better-paid spectators, but to turn them into owners.

The destination

So here is where we’re headed, named plainly before we build a single piece of it.

A society in which every citizen owns a real, voting share of the productive economy. Where your floor doesn’t need a wall to hold it up, because a share stays yours however cheaply the work gets done. Where you’re secure without depending on the economy having a job for you, and where you have a say — a literal vote — in what the machine you own actually builds. Where the ordinary person stands inside the economy instead of bracing against it. That is a shareholder society, and it’s the cargo this whole book means to deliver: not a richer citizen, but a citizen who is an owner.

It’s a long way from where we stand, and I won’t wave away the distance. The rest of this book is the how — every lever, every number, every hard trade-off, including the ones I don’t have clean answers to yet. And it starts with the thing itself: the floor, what it’s made of, and the simple piece of arithmetic that decides how high it sits. That’s the first step. Let’s take it.