I was recently in the hospital (that part of the story isn’t important) and had a Bitcoin book, A Progressive’s Case for Bitcoin: A Path Toward a More Just, Equitable, and Peaceful World, out on my desk to read while I was sitting around doing nothing. One of the nurses asked me if I “Was into Bitcoin?”. I naturally said “yes” enthusiastically and asked her if she wanted to talk about it. Her first comment was “Isn’t the bitcoin guy in jail?” I explained to her that “no there is no ‘bitcoin guy’” The guy who is in jail, who I’m assuming she meant Sam Bankman-Fried (SBF), although we didn’t clarify that, I explained to her, was a fraudster but not directly linked with bitcoin. I explained to her that Sam and his company FTX were more or less committing fraud on a level similar to Enron. She seemed to understand that.
Fighting basic narrative errors about bitcoin like this is important for bitcoin adoption. There is so much false news and when people don’t really have that much interest, this is the type of error they can make.
I also got to mention to her that there is a limit of 21 million bitcoin ever and it fixes the problem of governments stealing our savings via inflation. She did like that! She mentioned that she had a “lot of cash” and “wished the government would stop stealing things”. Not the most technical conversation, but I’m hoping that by.
1 . removing the connection of SBF/FTX to bitcoin and
2. Connecting the idea of bitcoin saving you from government created inflation, she might be more open to bitcoin the next time she hears about it.
She also mentioned that she “isn’t tech savvy” but somehow mentioned she has Venmo. You can buy bitcoin on Venmo (it’s not the favorite platform for the “hardcore” bitcoin folks but it works). So I did mention to her that she would be able to buy it there pretty easily.
If you read my previous post you will learn what problem bitcoin is trying to solve. But there is another thing that governments love to talk about when anyone mentions bitcoin or cryptocurrencies. To be clear on the difference between bitcoin and cryptocurrencies read this. The thing Governments love to bring up is a Central Bank Digital Currency or a CBDC for short.
What is a CBDC and what benefit does it have? The most important thing to know about a CBDC is it is 100% Government controlled, just like money today. It has no limit on how much of it there can be. Because of this they can create more new CBDC everyday and reduce the value of the ones you own. This is inflation and that is the problem that bitcoin solves by having a limit that is 21 million bitcoin ever. The fact that CBDC does not have a limit, means it is not a substitute for bitcoin and you should not be fooled by anyone on tv, or anywhere, saying a CBDC can replace bitcoin and now we don’t need bitcoin.
One thing a CBDC may do is either make settlements at the store faster or international settlements faster. Today international settlements usually go through a company like Western Union. It is very expensive to send money out of the country. Visa and Mastercard process most payments via their credit system and charge between 1.5%-4% to the businesses using their network. A CBDC could remove the need for Visa and Mastercard and for Western Union. Basically it could remove any intermediaries as a CBDC would be infinitely and immediately traceable. While to me all our money seems digital and traceable anyway, a CBDC would make it even more easily so. There may be a push from a government to use it as a form of punishment or denial of purchase for certain things which would be another option that opens up even more with the abilities of a CBDC. For example the government could say that buying meat is bad or buying more than 1000g/ month of meat is illegal and could limit your CBDC credit card to purchases of meat, or anything they wanted.
The main point I wanted to help people understand with that post is that a CBDC certainly does not do anything that would replace bitcoin or reduce inflation and could even potentially be used to control purchases by individuals.
To understand the reason behind why some people (like me) buy bitcoin you need to think about the problem we think bitcoin is trying to solve. When you use a government currency, like USD, the Government can effectively steal value from your bank account via money printing. How does this work?
To understand that you need to understand what the point of money is. Money is just a measurement of the value of something. We have all been trained that the value of things goes up over time because the price goes up over time. But just because a house rises in value by $100k over 5 years, does not mean its intrinsic value has risen. It’s the same house providing the same amount of shelter. It really shouldn’t gain value. What has really happened is the money, used to measure the value of the house, has lost value! It’d be like if you used a tape measure with 12 inches to 1 foot to measure a board and then you changed the tape measure to use 13 inches to 1 foot, where the foot is still the same length but each inch is smaller so you have “more inches”. But is the 1 foot board actually any more useful or longer if you use 13 shorter inches or 12 inches to 1 foot? No. This is how the government confuses us. They print more money and then our houses “go up” in value, but it’s because the measuring stick is changing. Why does the government do this though? They do it because that’s how they pay for the $1 trillion to $4 trillion budget deficit the Government has each year.
In WW1, while we were on the gold standard (every dollar was supposedly able to be converted back to gold at a bank), the government had to sell “war bonds” to pay for the war. This at least provided a little link between Americans turning over money for what they thought was a just cause. If people didn’t buy the bonds the government couldn’t pay for the war.
Since the US dollar was removed from the gold standard in 1971, the Government has had no restrictions on how much money they can print. The US government is able to fund any war ad infinitum via money printing. When this new money is printed the government uses it to buy good (ships, tanks, steel, sometimes roads, etc). Since they have unlimited purchasing power they can keep printing money until they can pay for what they need. Meanwhile, the average person might be unable to buy a new truck because the price of steel was pushed up by the government demanding 200 billion tons of steel for planes and warships.
When thinking about if you should buy bitcoin this is the fundamental issue you need to consider, how is my purchasing power being diluted via inflation?
Since bitcoin has a limited supply (21 million) as more US dollars are printed a single bitcoin’s value, measured in USD, or any other currency, will continue to go up.
This is due to those countries experiencing extremely high levels of inflation 50%-100% a year. I can’t even imagine what that would be like to live in. At 100% inflation, or even 50% you need a raise every paycheck! Your money would lose 1% of its value every week at 50% inflation.
While it seems like high inflation only happens in “far away” places with bad Governments that’s not the case. It has happened thousands of times in history
We, every person in the world, is in a fight with their own government to keep as much of the value they create as they can. The government explicitly taxes you, which we can debate but at least it is obvious. But the government also stealthy steals value from your bank account or savings via inflation and money printing that you have no control over.
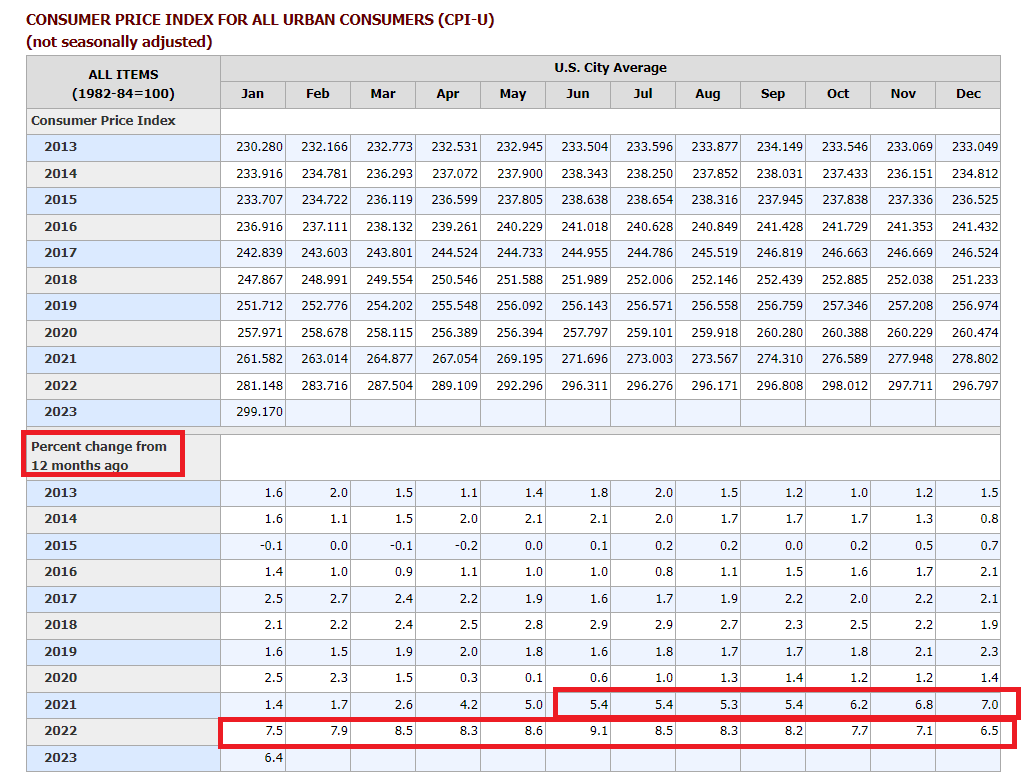
Because in the USA inflation has been a relatively small issue (1%-3%) for most of the last 25 years most people in the USA haven’t thought about wealth preservation much. Now that we’ve seen 10% inflation it’s new to people and they aren’t sure how to protect their purchasing power! A bond paying 5% is really losing 5% a year to inflation if inflation is 10%.
I know bitcoin is volatile but the inherent properties of it (ultimate scarcity, 21 million total coins ever), make it the best chance we have ever had to get out of the system and protect our wealth. If bitcoin doesn’t succeed then we will have lost every opportunity to preserve value!
I think that is a cause worth supporting, by buying and holding Bitcoin. And you’re not just supporting it, but you’re protecting your wealth!
I have written politicians and blog posts trying to encourage people to understand this while bitcoin is relatively cheap ($30k). I know once it is $50k or $100k more people will have Fear Of Missing Out and will buy in which could happen in the next year or 2. It’s best to learn about bitcoin when it’s price isn’t rising like crazy and you aren’t having FOMO.
If you’ve wondered this last year or 2 how to avoid losing value to inflation I’d enjoy talking to you more about bitcoin. I only recommend 1% of your net worth in it to start. So if you have $100,000 of net worth you can just buy $1,000 worth of bitcoin. That’s a small risk to be part of a monetary revolution that just might pay off.
I try to occasionally share my thoughts with politicians that represent me. Who knows how much they take heed of what we say? We all have our own pet projects that interest us and perhaps these don’t interest our politicians. I also try to share my thoughts with others through this blog and in person, in hopes that it will influence them to also come around to my way of thinking. That all being said, below is an email I recently sent to an Iowa state representative about Bitcoin. The history is this person is a Democrat. We have had a couple previous emails about Bitcoin and they were concerned about the environmental impacts of Bitcoin.
Dear Representative –
Quick thoughts for the night. I really hope you will continue to learn about bitcoin. It is a very important tool for protecting individuals’ wealth in the future. It is also helping people in developing countries today.
Perhaps you’ve seen this article sent to the US Congress by Human Rights leaders asking them to learn about how bitcoin is helping the poorest in the world.
The other point about bitcoin mining specifically is it helps reduce emissions. It does not add emissions. It uses the cheapest waste power. Most miners have load sharing agreements to turn off when excess power is needed. This is good for grid stability and for emissions reduction.
There is a bitcoin mining company in town partnering with Cedar Falls Utilities. I urge you to talk to both CFU and the miner about their agreement.
Finally, the US military paid for Jason Lowery to attend MIT for 2 years to learn about bitcoin and its national security implications. He released his thesis on this and I have read it and you can too.
Of note, I voted for Joe Biden in 2020 as we could not have another Trump. I have already decided I will not be voting for Biden again as he has proposed a 30% tax on bitcoin mining. This shows me he has no understanding of bitcoin. Or he knows it’s threatening to the USD and the government is fighting tooth and nail to ban it. Either way, I prefer freedom. I do not like the government devaluing my money every day with the $1T +deficit. I didn’t like it under, George Bush, under Obama, under Trump or under bBiden.
I hope others will consider writing to their local politicians to inform them of the good that Bitcoin does. They also need to know that they will not be getting votes if they are against something we are for. This applies to everything. It would be good for more people to write their politicians on all topics. Let this be an inspiration to you. If you want you could even copy this one and send it to your local politician.
“I think if everyone was to hold a little gold and silver (say 1%) it would send a message to the government that we are tired of inflation. Part of the goal of the FED raising interest rates is to get people to stop spending money and to invest it in bonds. I propose that instead of putting all your cash in bonds, what if many people considered buying just a $100 or $1,000 or $5,000 of physical gold or silver?”
The USA has ever increasing national debt. You’ve probably heard about it recently due to the silliness around raising the debt ceiling. Republicans always make a huge stink about it when they are in control of either the House or the Senate and there is a Democratic president but make no mention of deficits when a Republican is president. Anyway.
Regardless of which side of the aisle you sit on, every increasing debt is an issue because it is related to inflation. The government continually funding operations with printed money leads to inflation which reduces your purchasing power. In extreme cases this can lead to currency collapse as we have seen in Argentina, Sri Lanka and Lebanon recently.
When this happens, locals basically lose all savings they have in cash.
There are a few things to do to maintain purchasing power. One is to invest in the stock market. This has historically been a good place to hold money to maintain purchasing power over the long term. Holding German stocks after WWII, in Germany, even kept you mostly ahead of inflation!
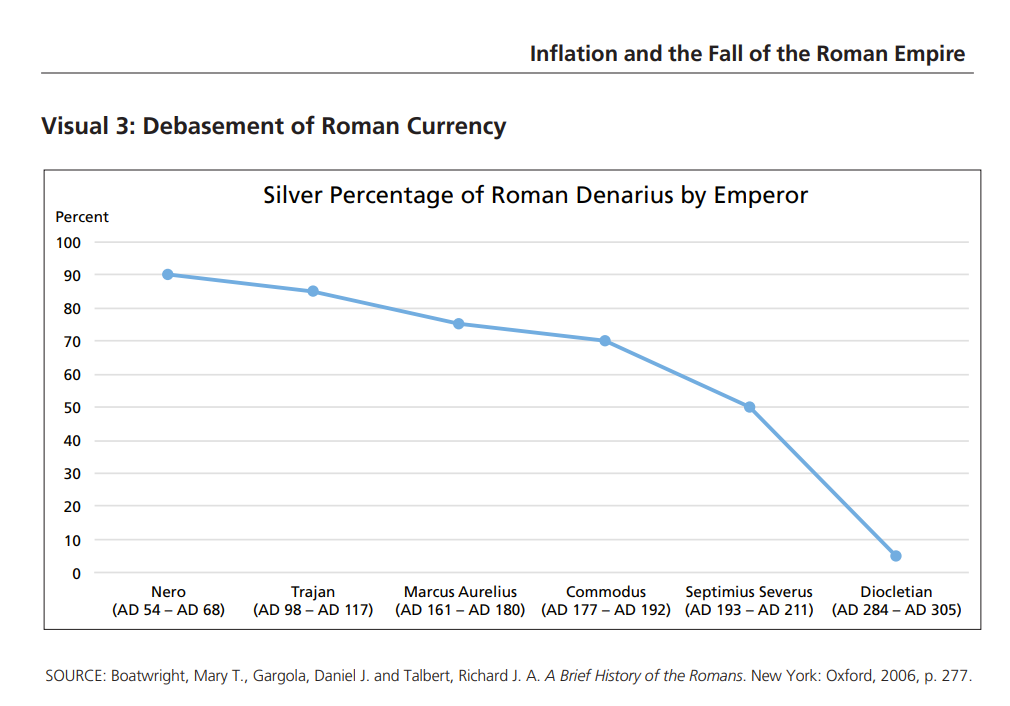
Historically, gold and silver have been money. But in the Roman empire silver coins were subject to debasement as emperors melted down existing coins and made 2 coins with the silver previously used for 1 coin and continued for 200 years until they completely destroyed the value of their currency.
The United States did this in 3 steps. In 1930 there was Executive Order 6102 which essentially forced Americans and “gold hoarders” to turn in their gold to the US government for a set price, $20.67 (equivalent to $433 in 2021) per troy ounce. The order also permitted any person to hold up to $100 in gold coins, a face value equivalent to 5 troy ounces (160 g) of gold valued at approximately $10,000 in 2020. The 1934 Gold Reserve Act subsequently changed the statutory gold content of the U.S. Dollar from $20.67 to $35 an ounce.
So, the Government basically paid people $20.67 for their gold, then said, you can’t buy it back, but if you could it would cost you $35/oz. Seems pretty crazy!
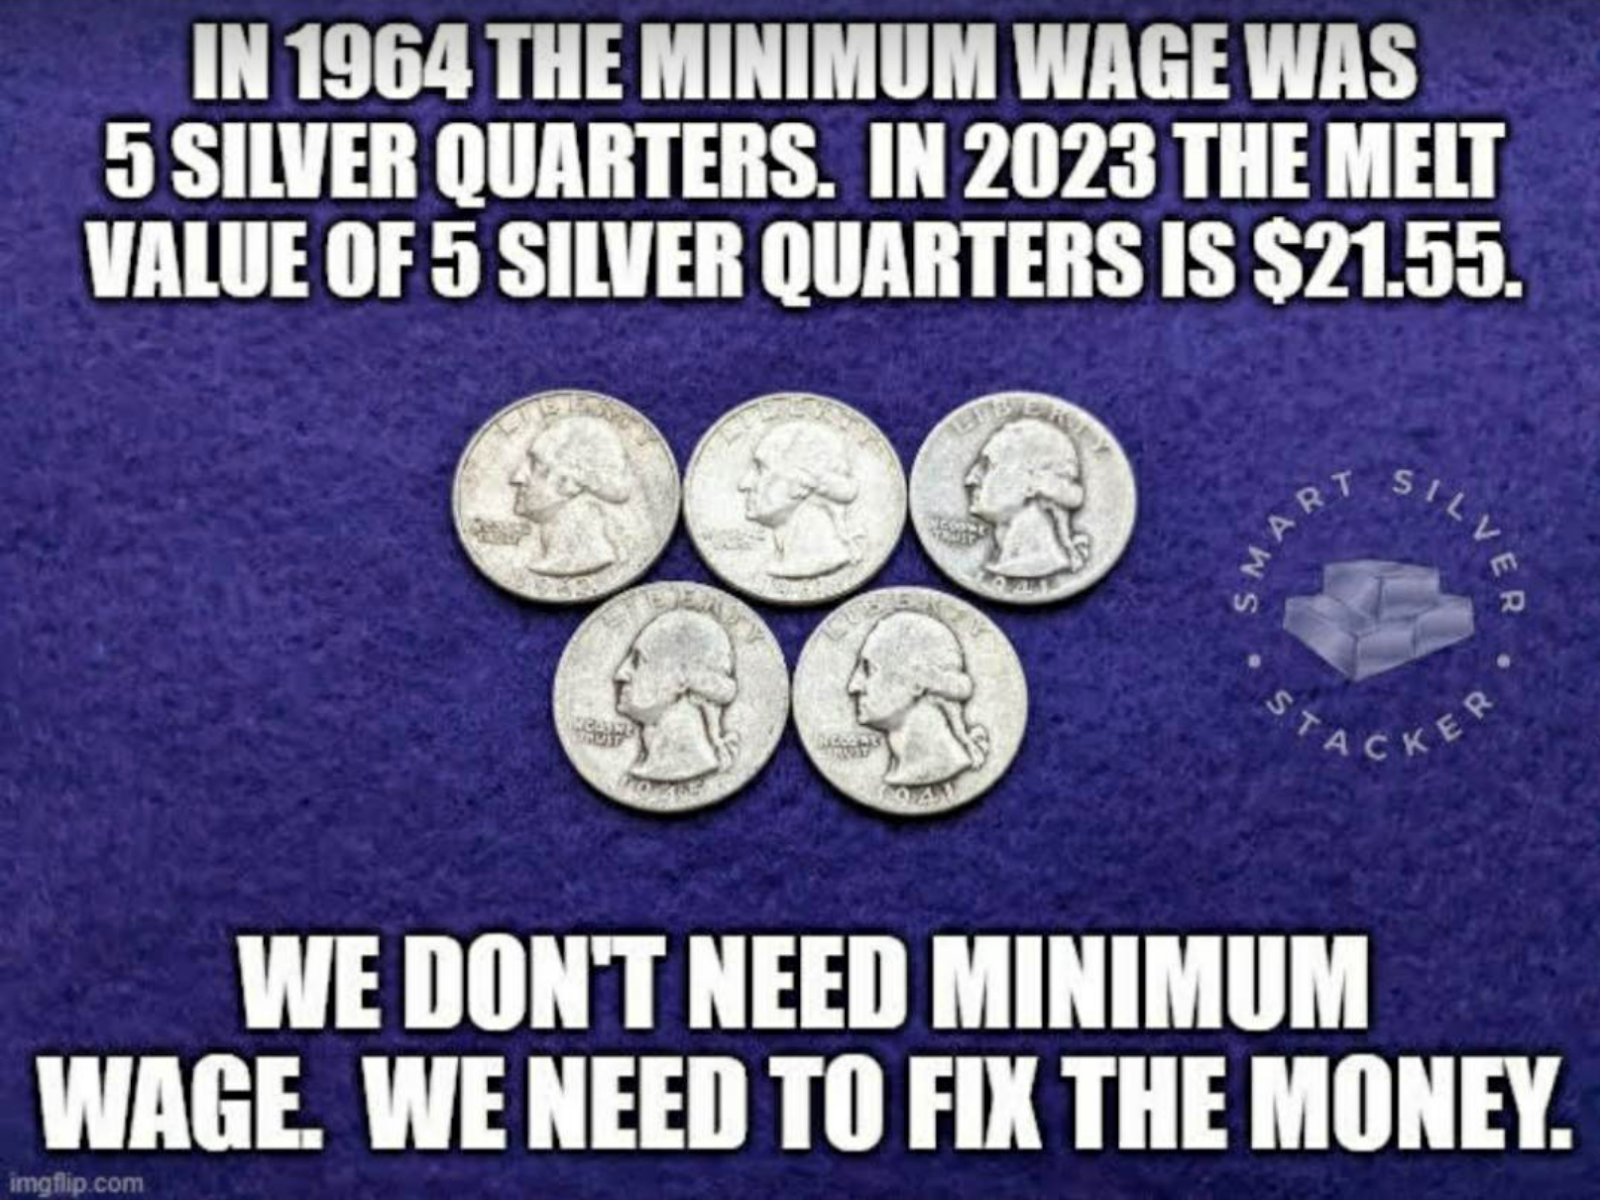
Step 2 of United States Currency debasement happened in 1964. Up to this time half dollars, quarters and dimes were made of 90% silver. After 1964 they were made mostly of cheaper copper.
The final straw that broke the dollar’s link with gold was in August 1971 Nixon ended the convertibility of US dollars to gold on the international market. Up until this time, while much of international trade was done in US dollars, technically, anytime any nation holding US dollars could ask the USA for the equivalent value of gold. Because the USA had been printing money for years it would have been impossible to redeem all the US dollars that existed for gold, so we basically said, “you can’t”. It was technically a type of default on the US dollar!
All the above context is just for historic purposes to get around to the point below and to mention why gold and silver are not used as money today. Governments always print more money than they can pay back. It happened in Rome, it happened in America, and it will likely happen again hundreds of years in the future (unless Bitcoin takes over as hard money, but that is a topic for a different post!)
Back to government debt, “Since 1800, 51 out of 52 countries with gross government debt greater than 130% have defaulted, either through restructuring, devaluation, high inflation or outright default. The IMF expects US government (USG) debt to GDP to be a record
This was partially due to the reduced GDP from Covid but also due to increased gov spending. In 2023 you can see Debt to GDP is “down” to only 120%.
So, what is the average person to do? As mentioned above, holding stocks is a good option. I personally do hold most of my wealth in stocks. Real Estate is another option that many people use. Bitcoin is also something I personally hold. I think Bitcoin has many long term benefits for wealth preservation. You can also hold bonds. But if you are holding a bond paying 5% and inflation continues up to 10% or 100%, like Argeintia, that won’t preserve your wealth. But this post is about physical Gold and Silver. I think holding physical gold and silver probably provides a little of a long term hedge against long term inflation. In the short term it certainly can be very volatile. But holding cash is always destined to go down over time. While over time, gold and silver are destined to go up, especially gold.
If you want to learn about buying physical gold and silver there are plenty of great youtube videos. Here is a video about buying silver I listened to recently.
I am only allocating a small percentage of my net worth towards physical gold and silver about 1% of total net worth, for now. In the grand scheme of things, I think this might not be very impactful. Some data says that “12% Of All Americans Own Gold, 14.7% Own Silver” .
I think if everyone was to hold a little gold and silver (say 1%) it would send a message to the government that we are tired of inflation. Part of the goal of the FED raising interest rates is to get people to stop spending money and to invest it in bonds. I propose that instead of putting all your cash in bonds, what if many people considered buying just $100 or $1,000 or $5,000 of physical gold or silver? Buying gold and silver would achieve the same end goal the government wants of removing money from the system, but then people would end up holding something of value, physical gold and silver, instead of bonds, which are currently returning 5% while inflation is at 7% or more yet. You are losing money holding bonds.
To be absolutely clear, I don’t think everyone should go sell all their stocks and put 100% into physical gold. But I think allocating 1% smartly for the reasons above is a pretty good idea.
I don’t have time here to review why I have been specifically saying “physical gold and silver” so many times. But this has been reviewed in many places.
Here is a good video and here is a good article about why physical gold or silver over paper gold and silver.
Personally I have used https://sdbullion.com/ to buy gold and silver online and always check their deals page. https://sdbullion.com/deals I get no commission off this, just sharing my experience. This guy also made a ranking of many of the online bullion dealers.
I have tried bringing up bitcoin to quite a few people over the last year (2022) and haven’t had much interest. I have finally realized that 99.9% of people won’t have any interest in Bitcoin until the price starts going up dramatically, perhaps around $100k people will start being interested again. I have decided that is fine. I am going to write this for people whenever they start becoming interested and wonder “How do I buy bitcoin?”
If you have recently seen Bitcoins price rise from $30,000 to $100,000 or more and are now having FOMO (fear of missing out) and you need to buy bitcoin NOW! Here is what you should do.
Go to the google play store (or apple store) on your phone and download “Cash App”.
Link your bank account.
Click “Buy bitcoin”.
Boom, you now own some bitcoin!
I recommend Cash App because they are a Bitcoin only company. There are many copies of Bitcoin like Bitcoin Cash (BCH), Bitcoin Satoshi Vision (BSV) and many others. Don’t be fooled. Only buy Bitcoin (BTC ticker symbol). Since Cash App only sells Bitcoin (BTC) this is not a problem. That is why I recommend Cash App for starting.
Now you can start learning about bitcoin. Luckily Cashapp also has news articles about bitcoin linked in it’s app so you can read there.
You can also follow Michael Saylor on Twitter. He has a lot of great information about bitcoin.
Now, owning bitcoin and holding it on the Cash App app isn’t the safest way to hold bitcoin. While Cashapp is relatively safe, there is still risk that Cashapp goes under.
An option now is to download Muun Wallet, also from the google play store. You can then transfer your bitcoin from Cashapp to Muun, if you want. You don’t have to do this. You can keep your money on Cash App. It’s like keeping money at a bank. Using Muun wallet is like keeping cash in a safe at your home.
Continue to learn more about Bitcoin through various articles. Don’t panic sell your Bitcoin if the price goes down from $100k to $50k or even $30k again! This is the nature of bitcoin, it is volatile.
Don’t FOMO into thousands and thousands of dollars of Bitcoin unless you are ready to temporarily lose 50% or more.
Don’t invest any more into Bitcoin than you are willing to lose. While I think it will be fine, it’s always possible something wild could happen and it could go to $0 (I doubt this but keeping all possibilities open).
Welcome to Bitcoin!
Oh, and you can always contact me with Bitcoin questions!
Through 1964 American quarters and dimes were made of 90% silver. Starting in 1965 the inner core is pure copper and the outer covering is copper mixed with nickel. I was discussing this with some friends so I decided to look up some history I recalled about Rome’s debasement of their currency. The first link I found was the below comment and this link to a FEDERAL RESERVE BANK OF ST. LOUIS work book for kids grade 8-12.
“Commodus (AD 177–AD 192) debased the Roman denarius to about 70 percent silver. Septimius Severus (AD 193–AD 211) debased the Roman denarius to about 50 percent silver. With the added currency, the government could pay for more soldiers and pay existing soldiers more.”
What is incredible is that the Romans “slowly” debased their currency by recalling the money, melting it down and reissuing with a lower percentage of silver. The US government did it quickly by going from 90% to 0% in 1 year! Subsequent dollars were created by adding numbers in the Fed ledger with nothing backing the new money!
Fort Knox holds about 4,580 metric tons of gold which is worth about $250 billion dollars. The US government budget was $6.27 trillion in 2022.
The Government budget deficit in 2022 was $1.38 trillion in 2022.
“A Cantillon effect is a change in relative prices resulting from a change in money supply.” –SWFI
Be Close to the President and Congress
Cantillon also had a theory in which the beneficiaries of the state creating the currency is based on the institutional setup of that state. This essentially means, “he who was close to the king and the wealthy”, likely benefited from the distributional choices of currency through the system. –SWFI
Realizing that the government is constantly creating new money and decreasing the purchasing power of the money you hold in your bank account, what is the average person to do?
I’ve had more conversations in 2022 and 2023 about “maintaining purchasing power” or “keeping my money from losing value” than ever before in my life, from people who’ve never asked questions like that before. I have to assume it’s because inflation has been between 5%-9% for the past 18 months in the USA, much much higher than the 0%-2% we’ve seen for the previous 10 years and longer.
The answers people are coming up with are the typical ones. I-bonds, which pay interest linked to inflation. A problem with them is you can only put $10,000/year per person into I-bonds.
The next likely targets are either treasury bills or high yield savings accounts. As of today a 180 day treasury bill is paying 4.5%. My personal high yield savings account is paying 4.1%. It’s not worth the extra hassle of buying treasury bills for me personally to get an extra 0.4% yield, but for some people it is. The problem is, with a 6.4% inflation rate over the last 6 months, you are still losing 2% of your purchasing power to inflation, which admittedly is the historic amount people have decided they are “OK” with losing, since the FED inflation target is 2%.
Many people buy real estate and get income from renters each month. Obviously not everyone wants to buy real estate or be a landlord. I have tried it. I am in the process of getting out of it. It wasn’t for me either!
Many people buy stocks as the classic inflation hedge. As we saw last year, stocks can also go down 20% or more in a year. But over long time frames they seem to be the best we have.
Gold is one of the best inflation hedges, over time. I have actually personally considered gold (and to a lesser extent silver) an interesting inflation hedge lately. Like all investing and savings, you need to evaluate the risks and rewards and determine what the right percentage is for each investment relative to your net worth and goals. For me 1% of net worth in gold and silver seems like a safe investment. I wouldn’t say anyone should be 50% or 100% into gold!
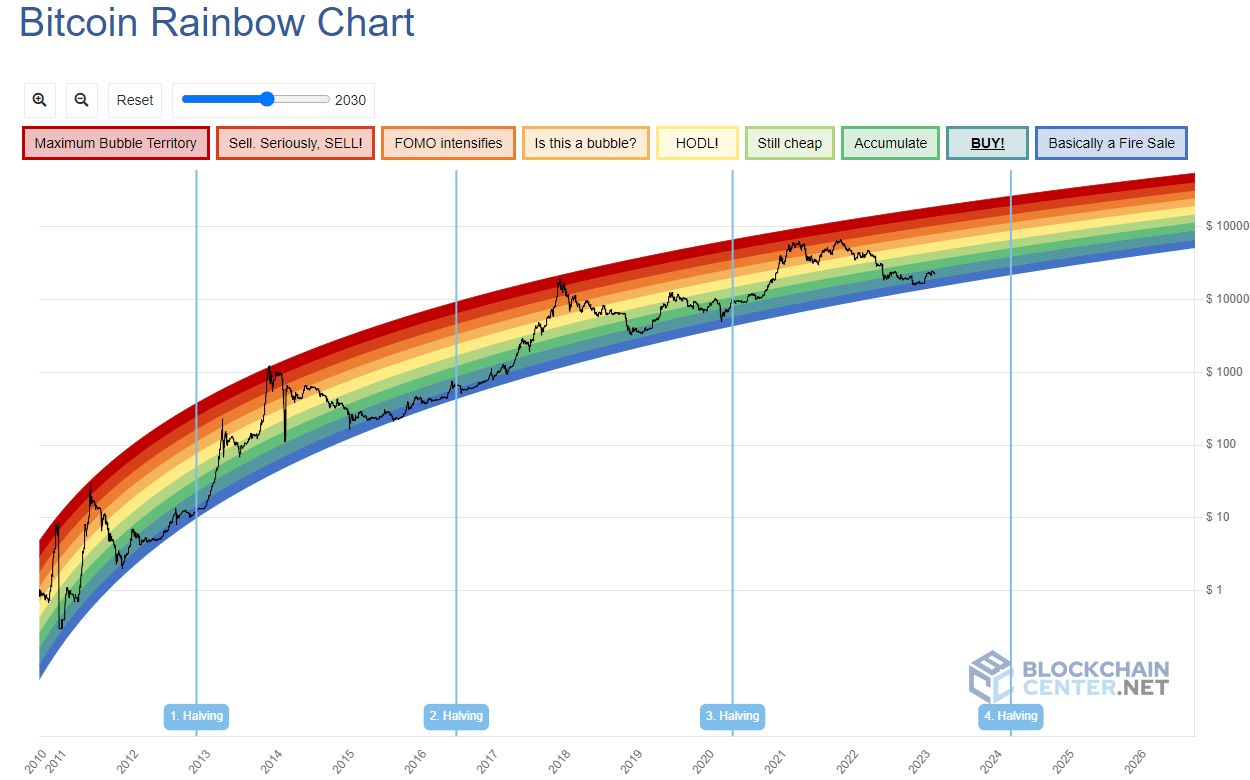
While a lot of these are ways to try to fight inflation there is another new way that might also work. Bitcoin. To me, it seems like a good inflation hedge, in the long term. I can see why many people are hesitant to get into it though. From a high of $69,000 in 2021 it fell all the way down to $15,000 earlier in 2023. It is back up to the low $23,000’s. But for people who just compare to the peak of $69,000 that’s still a long way down. But what people need to remember is, for most any investment, you don’t put every bit of your money in at the peak, usually! I bought some bitcoin for as low as $5,000 in 2018. I bought through the peak and the highest I paid for some bitcoin was $65,000, almost the peak! But that was only maybe $100 worth. I continued buying as it fell all through 2022 and even into the start of 2023. From June-Dec 2022 I bought for less than $20,000 per BTC. So now all that bitcoin is sitting in a profit. While my overall cost basis is about $28,000 and the value is sitting at $23,000, so I am down about 21%. But that is a lot less than the 66% you’d be down if you had bought every coin at the peak of 66%. I think that’s an important lesson for people to learn is that while there are volatile assets, if the asset makes sense, you should still consider allocating a percentage of your net worth towards it. I personally think people should consider 1% of Bitcoin a safe allocation. If you have $50,000 worth of assets that’s only $500. If you lose $500 will you be ruined? Probably not. As with every investment, you should only buy what you plan to keep for 10 years. You also shouldn’t sell when it goes down 50%. In fact you should expect it to go down 50%, whether it’s Bitcoin or stocks.Overall we need to better understand volatility. I believe as more people continue to add their wealth to Bitcoin, $10 at a time, its volatility will reduce and its value will continue to go up. This has already happened over many cycles. As you can see in the bitcoin rainbow chart below. It’s a simple chart tracking the highs and lows of bitcoin.
The best time to get into something is when fewer people are talking about it. A lot of people bought into bitcoin at the peak in 2021 when it was $69,000. That is the exact wrong time to learn about it and buy in because of fear! The best time to buy bitcoin, or anything, is when you have time to buy it and the price isn’t rising dramatically everyday and you get huge FOMO!
In 2017 I bought $100 worth of Bitcoin “just to learn about it”. It took me years to finally get around to learning more about it, as well as the price drastically rising to $40k, to pique my interest. I want to help others learn about it in a calmer state. Learning when it’s at a lower price also gives people a lower cost basis so there is a lot more room to go up! As more people pile into Bitcoin, and adoption is continuing, it will rise. Don’t buy in when the price rises from $40k to $60k in a month. You are already missing out at that point. If you do buy then, don’t be surprised when it falls back to $40k and you are out 50%. You’ve learned the wrong lesson. Start learning now while the price is low. Ask me anything! Start small and slow $50! $10! Good luck!
Abigail Disney (Disney Heiress worth $120 million) thinks that governments should tax the rich more. I guess the assumption is that then the government would do “good” with that money? But would they? Data says that giving money to people directly often is much better than having “someone else” decide what is best for them.
So, instead of deciding what is good for others, why doesn’t she embark on a personal redistribution? I proposed a similar, self funded, basic income idea to Mark Zuckerburg in 2017. He never took me up on that. Here is the basic setup.
$30k/year*500 people =$15 million *5 years = Cost of program $75 million over 5 years.
Since Abigail is worth $120 million and has rising stock, she will likely come out with over $75 million at the end of the project!
I am sure someone in Stockton who did this project would be happy to take some money to fund a larger project.
Or I am sure Andrew Yang would be happy to help facilitate such a project. We are waiting for a large donor to step up and fund such a large scale, long term project.
I had a short conversation with someone about EV’s (electric vehicles) who admitted that they didn’t know much about the current adoption/industry. I took it upon myself to gather a few highlights from 2022 as well as some info about exciting near term developments for 2023. Below are those articles!
A short deviation from all the EV stuff that will follow.
Porsche begins production of ‘e-fuel’ that could provide gas alternative amid EV push. Porsche said Tuesday that a pilot plant in Chile started production of the alternative fuel, as it aims to produce millions of gallons by mid-decade.
Tesla Cybertruck – Many Tesla fans are closely watching as tooling rolls into the Texas production plant, getting ready for Cybertruck production later in 2023!
Tesla takes delivery of army of robots to build Cybertruck
Vingroup Joint Stock Company is the largest conglomerate of Vietnam,focusing on technology, industry, real estate development, retail, and services ranging from healthcare to hospitality. The company was founded by property developer and entrepreneur Phạm Nhật Vượng.
It’s hard to tell how many cars Vinfast has sold in 2022. It sounds like only a few thousand. But hopefully they will start producing more in 2023! More EV companies the better.
The company said it sold 15,617 F150 Lightning EV pickups in 2022. Plans to sell many more in 2023.
Rivian
On a full-year 2022 basis, Rivian produced 24,337 electric vehicles and delivered 20,332 to customers. Rivian is a new EV only car (currently only making Trucks and SUV’s) company.
In 2022, 20,511 Volkswagen ID.4 (small electric sedan) were sold in the US, which is 22.5 percent more than in 2021 (16,742) and 6.8 percent of the brand’s total volume. Cumulatively, more than 37,000 ID.4 were delivered to customers
United states post office – Personally I think this is a great application for EV’s. standard daily route length. Can recharge at night. Should save USPS a lot of money.
o Postal Service anticipates increasing the quantity of purpose-built Next Generation Delivery Vehicles (NGDV) to a minimum of 60,000 of which at least 45,000 will be battery electric by 2028. NGDV acquisitions delivered in 2026 and thereafter expected to be 100% electric.
o Postal Service expects to purchase an additional 21,000 battery electric delivery vehicles through 2028, representing a mix of commercial-off-the-shelf (COTS) vehicles. Acquisitions delivered in 2026 through 2028 expected to be 100% electric.
Chinese EV companies – NIO, Xpeng, Li auto – are the 3 new big upcoming Chinese EV companies.
NIO – . NIO delivered 122,486 vehicles in 2022 in total, increasing by 34.0% year-over-year. Cumulative deliveries of NIO vehicles reached 289,556 as of December 31, 2022.
Li Auto – They are the 3rd hot Chinese EV car company. Honestly I don’t know much about them but apparently they delivered just slightly more EV’s than Nio or Xpeng in 2022 (Li Auto – 133,000 deliveries in 2022. See above link.
BYD – BYD auto is a legacy car company that has delivered a lot of hybrids in china.They sell more plug in hybrids than pure EV’s. but still a good company/force in EV world.
In 2022, BYD sold more than 1.85 million plug-in electric cars, more than tripling its 2021 result of 593,745. This makes the company the world’s largest manufacturer of rechargeable cars, although, in the case of all-electric cars, Tesla still has a significant edge (over 1.3 million deliveries).